
Introduction
IMPORTANT NOTICE – PLEASE READ CAREFULLY
In the event of a medical emergency, you or someone acting on your behalf must call one of the following telephone numbers listed below:
Elsewhere: +1-416-640-7865 collect
In the event of sickness or injury covered by this policy requiring hospitalisation, surgery, major diagnostic testing, or any medical treatment outside of the United Kingdom, you must contact Healix Assistance within 48 hours from the time of emergency. If Healix Assistance is not contacted, your claim may be denied or only partially covered.
This insurance covers medical expenses from sickness or injury, and losses arising from unexpected circumstances. Coverage is subject to certain limitations and exclusions, which are explained in this policy. It is important that you read and understand your policy.
You must call Healix Assistance to ensure coverage of certain expenses. If you fail to contact Healix Assistance, you may be responsible for a portion of the expenses.
In the event of an accident, injury or sickness, your prior medical history will be reviewed after a claim has been reported.
All benefit limits are expressed in Pound Sterling currency.
This policy is underwritten by certain Lloyd’s Underwriters. MSH International (UK) Ltd, performs enrolment and provides customer service. Emergency Assistance is provided by Healix Assistance.
Certain Lloyd’s Underwriters will pay the benefits stated in this policy, subject to all of its terms, conditions, limitations, exclusions and other provisions for reasonable and customary expenses that are incurred as a result of an unexpected sickness or injury up to the benefit maximum for that particular benefit, or to the overall policy maximum. All maximums stated in this policy are per insured person per consecutive 12-month period unless otherwise stated.
This policy is in force only if Healix Assistance confirms your coverage after receiving your enrolment information and the full monthly premium.If you have not received confirmation of coverage, immediately contact Healix Assistance by phone at 0204-615-3441 or +44 204 615 3441 (when dialling from outside the UK) or email studyinsured@healix.com
Please read your policy carefully before you travel.
For information about making a claim, or the status of a claim you have already sent us, call Healix Assistance Claims at Healix Assistance by phone at 0204-615-3441 or +44 204 615 3441 (when dialling from outside the UK) or email studyinsured@healix.com
Healthcare table of benefits - Core
Your healthcare scheme benefits are outlined in the table below.
Please note, the below benefits are:
-
subject to a total benefit limit per member, per scheme year of £2,000,000
Benefit limits apply per member, per scheme year unless otherwise stated. Once a benefit limit is reached, no further cover will be provided within the scheme year specified below. Cover for continued consultations, diagnostics or treatment in the next scheme year will be subject to all healthcare scheme terms and conditions.
| Benefit Type | Level of Cover | Benefit Note |
| Outpatient Diagnostics and Treatment | ||
Outpatient treatment |
Full cover | 1c |
Outpatient MRI, CT and PET scans following specialist referral |
Full cover | 2c |
| Inpatient and Day Case Treatment | ||
Specialist fees and hospital charges for inpatient and day case treatment |
Full cover | 3c |
| Cancer Treatment | ||
Cancer treatment |
Up to £25,000 per scheme year | 4c |
| Therapies | ||
Outpatient physiotherapy |
Full cover | 5c |
| Mental Health | ||
Outpatient mental health treatment |
Full cover | 6c |
Inpatient and day case mental health treatment |
Up to £10,000 per scheme year | 7c |
| Additional Benefits | ||
Sexual and Reproductive Health benefit Remote advice service with our in-network experts (up to 4 consultations per scheme year) Diagnostics following referral from our in-network experts (up to £500 per scheme year) |
Limited cover | 8c |
NHS cash benefit |
Up to £200 per night, up to £1,000 per scheme year | 9c |
Maternity care |
Up to £6,000 per scheme year | 10c |
Please note: the above benefits only apply when consultations, diagnostics or treatment take place in the UK unless specified otherwise.
Hospital Accommodation
- Hospital charges for room and board in a hospital, limited to the semi-private accommodation level.
- Emergency room fees.
- Hospital charges for out–patient services when medically required.
Medical Expenses
- Medical treatment by a legally licensed doctor, surgeon, anaesthetist, nurse practitioner, or registered graduate nurse (other than an immediate family member).
- Blood plasma, whole blood or oxygen including their administration.
- Ambulance services, covered up to the overall medical limit shown for the selected plan.
We will pay in full for MRI, CT and PET scans following specialist referral.
Back to topSpecialist Fees
We will pay specialist fees in full for inpatient and day case treatment. Cover is subject to our reasonable and customary fees.
Hospital Charges
We will pay hospital charges in full for the following:
- accommodation and nursing care for inpatient or day case treatment
- operating theatre and recovery room
- prescribed medicines and dressings, for use whilst an inpatient or for day case treatment
- eligible surgical appliances - for example, a knee brace following ligament surgery
- prosthesis or device which is inserted during eligible surgery
- pathology, radiology, diagnostics, MRI, CT and PET scans
- physiotherapy received during inpatient or day case treatment
- intensive care
- short-term dialysis when needed temporarily for sudden kidney failure resulting from an eligible condition or treatment
- skin and corneal grafts
We will pay for cancer treatment as outlined in the cancer cover explained section.
The insurers will provider reimbursement for the costs of medically necessary cancer treatment, combined limit of £25,000.
Back to topThe insurers will provide reimbursement for the costs of medically necessary physiotherapy treatment. Coverage is subject to the treatment being administered by a licensed and registered physiotherapist following a referral from a qualified medical practitioner.
Back to topWhen deemed essential by the attending doctor, the actual costs for:
- Visits to licensed psychiatrist, psychologist or social worker for the relief of actual symptoms.
- For hospital expenses due to psychological, mental or emotional disorders, suicide, any attempt at suicide, or intentionally self-inflicted injury.
- Fees billed separately for the services of a psychiatrist provided on an in-patient basis following an emergency.
- The initial visit to the doctor.
Psychological/Mental Health Benefit is covered up to a maximum limit as shown in the Schedule of Benefits for the selected plan.
Back to topWe will pay up to £10,000 per scheme year for eligible inpatient and day case mental health treatment ad inpatient specialist fees for the duration of your stay.
You must be under the direct care and supervision of a consultant psychiatrist, and receive authorisation from us in advance and in writing.
Back to topRemote Advice Service with Our In-Network Experts
We will pay for up to 4 remote advice appointments per scheme year with our in-network experts, following self-referral. This service can be used to discuss any health concern including conditions that are normally excluded from cover such as the menopause, andropause, sexual health concerns, fertility or contraception advice.
Diagnostics Following In-Network Expert Referral
We will pay up to £500 per scheme year for diagnostics that are recommended following a remote advice appointment with our in-network experts.
Refer to the sexual and reproductive health services section for further information on how to access these benefits.
Once either benefit limit has been reached, the scheme rules will apply as outlined in your exclusions and limitations.
Please note: The above benefits will not be subject to an excess, where this applies. Additional cover may be available outside of the above limits for eligible claims, please contact us for further information.
Back to topWhere an insured person receives treatment under the United Kingdom NHS, a hospital cash benefit is payable per night of inpatient confinement, subject to annual maximum.
NHS Cash Benefit is covered up to a maximum limit as shown in the Schedule of Benefits for the selected plan.
Back to topMedical treatment and services including hospital accommodations, prenatal care, delivery and complication are covered only where pregnancy occurs after the policy effective date.
Maternity Benefit is covered up to a maximum limit as shown in the Schedule of Benefits for the selected plan.
Back to topHealthcare table of benefits - Enhanced
Your healthcare scheme benefits are outlined in the table below.
Please note, the below benefits are:
-
subject to a total benefit limit per member, per scheme year of £5,000,000
Benefit limits apply per member, per scheme year unless otherwise stated. Once a benefit limit is reached, no further cover will be provided within the scheme year specified below. Cover for continued consultations, diagnostics or treatment in the next scheme year will be subject to all healthcare scheme terms and conditions.
| Benefit Type | Level of Cover | Benefit Note |
| Outpatient Diagnostics and Treatment | ||
Outpatient treatment |
Full cover | 1e |
Outpatient MRI, CT and PET scans following specialist referral |
Full cover | 2e |
| Hospital Accommodation | ||
Hospital accommodation |
Full cover | 3e |
| Cancer Treatment | ||
Cancer treatment |
Up to £25,000 per scheme year | 4e |
| Therapies | ||
Outpatient physiotherapy |
Full cover | 5e |
| Mental Health | ||
Outpatient mental health treatment |
Full cover | 6e |
Inpatient and day case mental health treatment |
Up to £12,000 per scheme year | 7e |
| Additional Benefits | ||
Sexual and Reproductive Health benefit Remote advice service with our in-network experts (up to 4 consultations per scheme year) Diagnostics following referral from our in-network experts (up to £500 per scheme year) |
Limited cover | 8e |
NHS cash benefit |
Up to £250 per night, up to £2,500 per scheme year | 9e |
Maternity care |
Up to £10,000 per scheme year | 10e |
Please note: the above benefits only apply when consultations, diagnostics or treatment take place in the UK unless specified otherwise.
Hospital Accommodation
- Hospital charges for room and board in a hospital, limited to the semi-private accommodation level.
- Emergency room fees.
- Hospital charges for out–patient services when medically required.
Medical Expenses
- Medical treatment by a legally licensed doctor, surgeon, anaesthetist, nurse practitioner, or registered graduate nurse (other than an immediate family member).
- Blood plasma, whole blood or oxygen including their administration.
- Ambulance services, covered up to the overall medical limit shown for the selected plan.
We will pay in full for MRI, CT and PET scans following specialist referral.
Back to top- Hospital charges for room and board in a hospital, limited to the semi-private accommodation level.
- Emergency room fees.
- Hospital charges for out–patient services when medically required.
We will pay for cancer treatment as outlined in the cancer cover explained section.
The insurers will provider reimbursement for the costs of medically necessary cancer treatment, combined limit of £25,000.
Back to topThe insurers will provide reimbursement for the costs of medically necessary physiotherapy treatment. Coverage is subject to the treatment being administered by a licensed and registered physiotherapist following a referral from a qualified medical practitioner.
Back to topWhen deemed essential by the attending doctor, the actual costs for:
- Visits to licensed psychiatrist, psychologist or social worker for the relief of actual symptoms.
- For hospital expenses due to psychological, mental or emotional disorders, suicide, any attempt at suicide, or intentionally self-inflicted injury.
- Fees billed separately for the services of a psychiatrist provided on an in-patient basis following an emergency.
- The initial visit to the doctor.
Psychological/Mental Health Benefit is covered up to a maximum limit as shown in the Schedule of Benefits for the selected plan.
Back to topWe will pay up to £12,000 per scheme year for eligible inpatient and day case mental health treatment ad inpatient specialist fees for the duration of your stay.
You must be under the direct care and supervision of a consultant psychiatrist, and receive authorisation from us in advance and in writing.
Back to topRemote Advice Service with Our In-Network Experts
We will pay for up to 4 remote advice appointments per scheme year with our in-network experts, following self-referral. This service can be used to discuss any health concern including conditions that are normally excluded from cover such as the menopause, andropause, sexual health concerns, fertility or contraception advice.
Diagnostics Following In-Network Expert Referral
We will pay up to £500 per scheme year for diagnostics that are recommended following a remote advice appointment with our in-network experts.
Refer to the sexual and reproductive health services section for further information on how to access these benefits.
Once either benefit limit has been reached, the scheme rules will apply as outlined in your exclusions and limitations.
Please note: The above benefits will not be subject to an excess, where this applies. Additional cover may be available outside of the above limits for eligible claims, please contact us for further information.
Back to topWhere an insured person receives treatment under the United Kingdom NHS, a hospital cash benefit is payable per night of inpatient confinement, subject to annual maximum.
NHS Cash Benefit is covered up to a maximum limit as shown in the Schedule of Benefits for the selected plan.
Back to topMedical treatment and services including hospital accommodations, prenatal care, delivery and complication are covered only where pregnancy occurs after the policy effective date.
Maternity Benefit is covered up to a maximum limit as shown in the Schedule of Benefits for the selected plan.
Back to topReimbursement table of benefits - Core
Your scheme benefits are outlined in the table below.
Please note, the below benefits are:
-
subject to a total benefit limit per member, per scheme year of £2,000,000
Benefit limits apply per member, per scheme year unless otherwise stated. Once a benefit limit is reached, no further cover will be provided within the scheme year specified below.
| Dental, Vision and Physical Care | Level of cover | Benefit note |
Dental visit |
Up to £75 per scheme year | C1 |
Emergency dental treatment |
Up to £500 per scheme year | C2 |
Emergency vision care |
Up to £200 per scheme year | C3 |
Physical exam |
Up to £150 per scheme year | C4 |
Prescription drugs |
Full cover | C5 |
Hospital out of pocket expenses |
Up to £100 per scheme year | C6 |
| Travel related costs | ||
Air and ground transport |
Full cover | C7 |
Transport to bedside |
Cost of 2 relatives economy air fare | C8 |
Passport or documents |
Up to £500 per scheme year | C9 |
Baggage and personal effects |
Up to £2,500 per scheme year | C10 |
Baggage delay |
Up to £250 per scheme year | C11 |
Missed departure |
Up to £10,000 per scheme year | C12 |
Delayed departure |
Up to £200 per scheme year | C13 |
Trip cancellation |
Up to £10,000 per scheme year | C14 |
| Additional reimbursement benefits | ||
Accidental death |
Up to £25,000 per member | C15 |
Repatriation of remains |
Up to £5,000 per member | C16 |
Personal liability |
Up to £1,500,000 | C17 |
Personal money |
Up to £150 per scheme year | C18 |
Valuables or electronics |
Up to £250 per scheme year | C19 |
Single article limit |
Up to £250 per scheme year | C20 |
Unused course fees |
Up to £8,000 per scheme year | C21 |
Note: The above benefits only apply when the covered person has treatment in the UK, or when temporarily abroad on holiday or business up to specified limits.
One annual dental examination in any consecutive 12-month period provided a minimum of six (6) months of consecutive coverage has been purchased.
Dental Visit Benefit is covered up to a maximum limit as shown in the Schedule of Benefits for the selected plan.
Back to topWhen an accidental blow to the mouth or face results in Injury to an Insured Person, the Insurer will pay for the Emergency dental treatment necessary to restore or replace permanently attached artificial teeth or sound natural teeth lost or damaged in an Accident, and for which dental treatment is initiated within thirty (30) days following an Accident and completed within the policy term. Detailed medical documentation from a Physician or dentist must be provided to support an Insured Person’s claim. All indemnity payable under this section is subject to a maximum as based on the selected plan.
Back to topUp to £200 for one eye examination because of an accident by a licensed optometrist or ophthalmologist in any consecutive 12-month period provided a minimum of six (6) months of consecutive coverage has been purchased.
Back to topUp to £150 for one annual medical examination by a physician in any consecutive 12-month period provided a minimum of six (6) months of consecutive coverage has been purchased.
Back to topDrugs, including injectable drugs and sera, that can only be obtained upon medical prescription, that are prescribed by a doctor and that are supplied by a licensed pharmacist when medically necessary for emergency medical treatment. This benefit is limited to a 60-day supply per prescription, unless you are hospitalised. Ongoing prescriptions for chronic conditions and over-the-counter drugs or medicines are not covered.
Prescription Drug Benefit is covered up to a maximum limit as shown in the Schedule of Benefits for the selected plan.
Back to topGround Transportation
Up to overall policy limit for a licensed ground ambulance service to the nearest medical facility for medical treatment as the result of a covered emergency.
Air Transportation
This benefit must be pre-approved and arranged in advance by Healix Assistance.
- Air ambulance to the nearest appropriate medical facility or to a hospital or to a hospital in your home country for immediate emergency medical treatment.
- Transport on a licensed airline with an attendant (when required) for your emergency return to your home country or your state of residence for immediate medical treatment.
- The fare for additional seats to accommodate a stretcher, if required, to return you to your home country or your state of residence.
- Up to the cost of a one-way economy airfare to return you to your home country or your state of residence following an emergency and after you are fit to travel.
The cost of ground transportation before or after the flight or for connecting flights as well as the cost of a medical attendant, if required, are included in this benefit.
Back to topThis benefit must be pre-approved and arranged by Healix Assistance.
Covered for a single round-trip economy airfare by the most direct and economical route, and reasonable commercial living expenses for up to two (2) immediate family members to:
- Be with you if you are hospitalized as the result of a covered emergency and the attending physician provides written certification that the situation was serious enough to warrant the visit; or
- Identify you prior to the release of your body, where necessary.
Benefit is paid to the maximum limit of £500 for reasonable extra travel and accommodation expenses (room) only for the Insured while having to get emergency or temporary documents during the trip, including:
- Passport
- Visas
- Driving license
- Green card
Coverage is provided for accidental loss, theft, or damage of personal effects and valuables for incidents occurring throughout the duration of your trip.
Baggage & Personal Effects is covered up to a maximum limit as shown in the Schedule of Benefits for the selected plan.
Back to topIn the event that the insured’s checked baggage is temporary lost in transit during a trip and not returned to you within 8 hours of your arrival at your destination, we will pay for :
- Emergency replacement of clothing.
- Medication, and
- Toiletries.
To file a claim, the insured must supply proof of delay of checked baggage from the common carrier and original purchase receipts.
Baggage Delay Benefit is covered up to a maximum limit as shown in the Schedule of Benefits for the selected plan.
Back to topBenefit is paid in the event of a missed departure of your trip at an airport, port or rail terminal due to :
- The failure of other scheduled public transport; or
- The vehicle you are travelling in breaking down or being involved in an accident; or
- An accident or breakdown which happens ahead of you on a motorway or dual carriageway, and which causes an unexpected delay to the vehicle you are travelling in.
Missed Departure Benefit is covered up to a maximum limit as shown in the Schedule of Benefits for the selected plan.
Back to topBenefit is paid if a scheduled trip departure of the public transport on which you are booked to travel on accordingly to your itinerary is delayed by at least 12 hours due to:
- Strike or industrial action; or
- Adverse weather conditions; or
- Mechanical breakdown of or a technical fault occurring in the scheduled public transport on you are booked to travel.
Departure Benefit is covered up to a maximum limit as shown in the Schedule of Benefits for the selected plan.
Back to topIf cancellation of your trip becomes necessary and unavoidable, we will cover unused and non-recoverable expenses- including travel, tuition, and accommodations up to the maximum limit as shown in the Schedule of Benefits for the selected plan.
Should your trip be cut short for one of the following reasons, we will cover unused and non-recoverable expenses (such as travel, tuition, accommodation, and pre-paid activities) that you have paid or are legally obligated to pay, up to the maximum limit as shown in the Schedule of Benefits for the selected plan.
Reasons for cancelling or cutting your trip short:
• the death, bodily injury, serious illness or complication of pregnancy and childbirth of:
- You; or
- A close relative; or
- Any person you are arranged to stay with during your trip.
• The police have asked you to stay at your home due to serios damage to your home or business.
• The government of your country of temporary residence or other regulatory authority in a country in which you are travelling to/from has issued travel restrictions. This excludes where advice is issued due to a pandemic, epidemic or regional quarantine if this advice came into force after you purchased this insurance or booked the trip (whichever is the later).
• Compulsory personal quarantine of you or your travelling companion(s).
• Jury service attendance or being called as a witness at a Court of Law (other than in an advisory or professional capacity) of you or your travelling companion(s).
• Your redundancy.
• Your exam failure.
• The non-issuance of a student or travel visa required for your trip, provided you were eligible to make such an application, for reasons beyond your control.
Back to topAccidental Death & Dismemberment Benefit is covered up to a maximum limit as shown in the Schedule of Benefits for the selected plan.
Common Carrier Accident
Should you incur either loss of life or a dismemberment described in the Loss Schedule as a result of an injury sustained while riding as a fare paying passenger on a common carrier.
24 Hour Accident
If injury results in any of the following losses within 365 days after the date of the accident other than due to a common carrier, the policy provides the benefits indicated below.
| Loss | % of Principle sum |
|
Loss of life |
100% |
|
Loss of both hands or both feet |
100% |
|
Loss of entire sight of both eyes |
100% |
|
Loss of one hand and one foot |
100% |
|
Loss of one hand and the entire sight of one eye |
100% |
|
Loss of one foot and the entire sight of one eye |
100% |
|
Loss of one arm |
50% |
|
Loss of one leg |
50% |
|
Loss of one hand |
50% |
|
Loss of one foot |
50% |
|
Loss of entire sight of one eye |
50% |
|
Loss of thumb or index finger of the same hand |
33.33% |
|
Loss of speed and hearing |
100% |
|
Loss of speech or hearing |
50% |
|
Quadriplegia, paraplegia, hemiplegia |
100% |
|
Loss of use of both arms or both hands |
100% |
|
Loss of use of one hand or one foot |
50% |
|
Loss of use of one arm or one leg |
50% |
Accidental Death & Dismemberment Benefit is covered up to a maximum limit as shown in the Schedule of Benefits for the selected plan.
Disappearance
If your body has not been found within one year of your disappearance (as documented by a competent governmental or law enforcement agency), you shall, in the absence of any evidence to the contrary, be deemed to have suffered loss of life.
Beneficiary
The benefit for loss of life is payable to the deceased person’s estate. If you are under age 16, the benefit is payable to your parent or legal guardian. We may ask the claimant to prove their relationship to the deceased.
Trauma Counselling
Expenses incurred for up to six (6) trauma counselling sessions if you suffer a loss under Accidental Death & Dismemberment within 90 days from the date of an accident which occurred during the coverage period.
Back to topIn the event of your death as a result of a covered accident or unexpected sickness and when approved and arranged in advance by StudyInsured™ Assistance.
- The actual cost incurred for the preparation of remains and transportation (including a standard shipping container) to your home country; or
- Cremation and/or burial at the place of death.
The cost of the casket, urn or funeral is not covered.
Repatriation of Remains Benefit is covered up to a maximum limit as shown in the Schedule of Benefits for the selected plan.
Back to topIn the event of a claim made against you during the period of insurance, we will provide coverage for your legal liability, including damages and costs for:
- Accidental bodily injury, death or illness to any person .
- Accidental loss of or damage to property that does not belong to you, and is not in the care, custody or control of you, a close relative, travelling companion, anytone in you employment or any member of your household.
- Accidental loss of or damage to property you are renting as your temporary trip accommodation, provided you do not own it.
Personal Liability Benefit is covered up to a maximum limit as shown in the Schedule of Benefits for the selected plan.
Back to topCoverage is provided for accidental loss of personal currency during the trip.
Personal Money (Cash) Benefit is covered up to a maximum limit as shown in the Schedule of Benefits for the selected plan.
Back to topCoverage for any individual article, including pairs or sets, is subject to the per-item limit. An Individual Article may include:
- Camera
- Laptop
- Jewelry
Single Article Limit Benefit is covered up to a maximum limit as shown in the Schedule of Benefits for the selected plan.
Back to topWe provide coverage for non-refundable tuition and course fees- should you be forced to cancel or cut your trip short due to a covered event. Reimbursement is limited to the portion of the fees that cannot be recovered from the education provider or institution.
Unused Course Fees Benefit is covered up to a maximum limit as shown in the Schedule of Benefits for the selected plan.
Back to topReimbursement table of benefits - Enhanced
Your scheme benefits are outlined in the table below.
Please note, the below benefits are:
-
subject to a total benefit limit per member, per scheme year of £5,000,000
Benefit limits apply per member, per scheme year unless otherwise stated. Once a benefit limit is reached, no further cover will be provided within the scheme year specified below.
| Dental, Vision and Physical Care | Level of cover | Benefit note |
Dental visit |
Up to £150 per scheme year | E1 |
Emergency dental treatment |
Up to £750 per scheme year | E2 |
Emergency vision care |
Up to £200 per scheme year | E3 |
Physical exam |
Up to £150 per scheme year | E4 |
Hospital out of pocket expenses |
Up to £150 per scheme year | E5 |
Prescription drugs |
Full cover | E6 |
| Travel related costs | ||
Air and ground transport |
Full cover | E7 |
Transport to bedside |
Cost of 2 relatives economy air fare | E8 |
Passport or documents |
Up to £500 per scheme year | E9 |
Baggage and personal effects |
Up to £2,500 per scheme year | E10 |
Baggage delay |
Up to £250 per scheme year | E11 |
Missed departure |
Up to £10,000 per scheme year | E12 |
Delayed departure |
Up to £200 per scheme year | E13 |
Trip cancellation |
Up to £10,000 per scheme year | E14 |
| Additional reimbursement benefits | ||
Accidental death |
Up to £50,000 per member | E15 |
Repatriation of remains |
Up to £10,000 per member | E16 |
Personal liability |
Up to £2,500,000 | E17 |
Personal money |
Up to £250 per scheme year | E18 |
Valuables or electronics |
Up to £300 per scheme year | E19 |
Single article limit |
Up to £300 per scheme year | E20 |
Unused course fees |
Up to £10,000 per scheme year | E21 |
Note: The above benefits only apply when the covered person has treatment in the UK, or when temporarily abroad on holiday or business up to specified limits.
One annual dental examination in any consecutive 12-month period provided a minimum of six (6) months of consecutive coverage has been purchased.
Dental Visit Benefit is covered up to a maximum limit as shown in the Schedule of Benefits for the selected plan
Back to topWhen an accidental blow to the mouth or face results in Injury to an Insured Person, the Insurer will pay for the emergency dental treatment necessary to restore or replace permanently attached artificial teeth or sound natural teeth lost or damaged in an accident, and for which dental treatment is initiated within thirty (30) days following an accident and completed within the policy term.
Detailed medical documentation from a physician or dentist must be provided to support an Insured Person’s claim. All indemnity payable under this section is subject to a maximum as based on the selected plan.
Back to topUp to £200 for one eye examination because of an accident by a licensed optometrist or ophthalmologist in any consecutive 12-month period provided a minimum of six (6) months of consecutive coverage has been purchased.
Back to topUp to £150 for one annual medical examination by a physician in any consecutive 12-month period provided a minimum of six (6) months of consecutive coverage has been purchased.
Back to topDrugs, including injectable drugs and sera, that can only be obtained upon medical prescription, that are prescribed by a doctor and that are supplied by a licensed pharmacist when medically necessary for emergency medical treatment. This benefit is limited to a 60-day supply per prescription, unless you are hospitalised. Ongoing prescriptions for chronic conditions and over-the-counter drugs or medicines are not covered.
Prescription Drug Benefit is covered up to a maximum limit as shown in the Schedule of Benefits for the selected plan.
Back to topGround Transportation
Up to overall policy limit for a licensed ground ambulance service to the nearest medical facility for medical treatment as the result of a covered emergency.
Air Transportation
This benefit must be pre-approved and arranged in advance by Healix Assistance.
- Air ambulance to the nearest appropriate medical facility or to a hospital or to a hospital in your home country for immediate emergency medical treatment.
- Transport on a licensed airline with an attendant (when required) for your emergency return to your home country or your state of residence for immediate medical treatment.
- The fare for additional seats to accommodate a stretcher, if required, to return you to your home country or your state of residence.
- Up to the cost of a one-way economy airfare to return you to your home country or your state of residence following an emergency and after you are fit to travel.
The cost of ground transportation before or after the flight or for connecting flights as well as the cost of a medical attendant, if required, are included in this benefit.
Back to topThis benefit must be pre-approved and arranged by Healix Assistance.
Covered for a single round-trip economy airfare by the most direct and economical route, and reasonable commercial living expenses for up to two (2) immediate family members to:
- Be with you if you are hospitalized as the result of a covered emergency and the attending physician provides written certification that the situation was serious enough to warrant the visit; or
- Identify you prior to the release of your body, where necessary.
Benefit is paid to the maximum limit of £500 for reasonable extra travel and accommodation expenses (room) only for the Insured while having to get emergency or temporary documents during the trip, including:
- Passport
- Visas
- Driving license
- Green card
Coverage is provided for accidental loss, theft, or damage of personal effects and valuables for incidents occurring throughout the duration of your trip.
Baggage & personal effects is covered up to a maximum limit as shown in the Schedule of Benefits for the selected plan.
Back to topIn the event that the insured’s checked baggage is temporary lost in transit during a trip and not returned to you within 8 hours of your arrival at your destination, we will pay for :
- Emergency replacement of clothing.
- Medication, and
- Toiletries.
To file a claim, the insured must supply proof of delay of checked baggage from the common carrier and original purchase receipts.
Baggage delay benefit is covered up to a maximum limit as shown in the schedule of benefits for the selected plan.
Back to topBenefit is paid in the event of a missed departure of your trip at an airport, port or rail terminal due to :
- The failure of other scheduled public transport; or
- The vehicle you are travelling in breaking down or being involved in an accident; or
- An accident or breakdown which happens ahead of you on a motorway or dual carriageway, and which causes an unexpected delay to the vehicle you are travelling in.
Missed departure benefit is covered up to a maximum limit as shown in the Schedule of Benefits for the selected plan.
Back to topBenefit is paid if a scheduled trip departure of the public transport on which you are booked to travel on accordingly to your itinerary is delayed by at least 12 hours due to:
- Strike or industrial action; or
- Adverse weather conditions; or
- Mechanical breakdown of or a technical fault occurring in the scheduled public transport on you are booked to travel.
Departure benefit is covered up to a maximum limit as shown in the Schedule of Benefits for the selected plan.
Back to topIf cancellation of your trip becomes necessary and unavoidable, we will cover unused and non-recoverable expenses- including travel, tuition, and accommodations up to the maximum limit as shown in the Schedule of Benefits for the selected plan.
Should your trip be cut short for one of the following reasons, we will cover unused and non-recoverable expenses (such as travel, tuition, accommodation, and pre-paid activities) that you have paid or are legally obligated to pay, up to the maximum limit as shown in the Schedule of Benefits for the selected plan.
Reasons for cancelling or cutting your trip short:
• the death, bodily injury, serious illness or complication of pregnancy and childbirth of:
- You; or
- A close relative; or
- Any person you are arranged to stay with during your trip.
• The police have asked you to stay at your home due to serios damage to your home or business.
• The government of your country of temporary residence or other regulatory authority in a country in which you are travelling to/from has issued travel restrictions. This excludes where advice is issued due to a pandemic, epidemic or regional quarantine if this advice came into force after you purchased this insurance or booked the trip (whichever is the later).
• Compulsory personal quarantine of you or your travelling companion(s).
• Jury service attendance or being called as a witness at a Court of Law (other than in an advisory or professional capacity) of you or your travelling companion(s).
• Your redundancy.
• Your exam failure.
• The non-issuance of a student or travel visa required for your trip, provided you were eligible to make such an application, for reasons beyond your control.
Back to topAccidental Death & Dismemberment Benefit is covered up to a maximum limit as shown in the Schedule of Benefits for the selected plan.
Common Carrier Accident
Should you incur either loss of life or a dismemberment described in the Loss Schedule as a result of an injury sustained while riding as a fare paying passenger on a common carrier.
24 Hour Accident
If injury results in any of the following losses within 365 days after the date of the accident other than due to a common carrier, the policy provides the benefits indicated below.
| Loss | % of Principle sum |
|
Loss of life |
100% |
|
Loss of both hands or both feet |
100% |
|
Loss of entire sight of both eyes |
100% |
|
Loss of one hand and one foot |
100% |
|
Loss of one hand and the entire sight of one eye |
100% |
|
Loss of one foot and the entire sight of one eye |
100% |
|
Loss of one arm |
50% |
|
Loss of one leg |
50% |
|
Loss of one hand |
50% |
|
Loss of one foot |
50% |
|
Loss of entire sight of one eye |
50% |
|
Loss of thumb or index finger of the same hand |
33.33% |
|
Loss of speed and hearing |
100% |
|
Loss of speech or hearing |
50% |
|
Quadriplegia, paraplegia, hemiplegia |
100% |
|
Loss of use of both arms or both hands |
100% |
|
Loss of use of one hand or one foot |
50% |
|
Loss of use of one arm or one leg |
50% |
Accidental Death & Dismemberment Benefit is covered up to a maximum limit as shown in the Schedule of Benefits for the selected plan.
Disappearance
If your body has not been found within one year of your disappearance (as documented by a competent governmental or law enforcement agency), you shall, in the absence of any evidence to the contrary, be deemed to have suffered loss of life.
Beneficiary
The benefit for loss of life is payable to the deceased person’s estate. If you are under age 16, the benefit is payable to your parent or legal guardian. We may ask the claimant to prove their relationship to the deceased.
Trauma Counselling
Expenses incurred for up to six (6) trauma counselling sessions if you suffer a loss under Accidental Death & Dismemberment within 90 days from the date of an accident which occurred during the coverage period.
Back to topIn the event of your death as a result of a covered accident or unexpected sickness and when approved and arranged in advance by StudyInsured™ Assistance.
- The actual cost incurred for the preparation of remains and transportation (including a standard shipping container) to your home country; or
- Cremation and/or burial at the place of death.
The cost of the casket, urn or funeral is not covered.
Repatriation of Remains Benefit is covered up to a maximum limit as shown in the Schedule of Benefits for the selected plan.
Back to topIn the event of a claim made against you during the period of insurance, we will provide coverage for your legal liability, including damages and costs for:
- Accidental bodily injury, death or illness to any person .
- Accidental loss of or damage to property that does not belong to you, and is not in the care, custody or control of you, a close relative, travelling companion, anytone in you employment or any member of your household.
- Accidental loss of or damage to property you are renting as your temporary trip accommodation, provided you do not own it.
Personal Liability Benefit is covered up to a maximum limit as shown in the Schedule of Benefits for the selected plan.
Back to topCoverage is provided for accidental loss of personal currency during the trip.
Personal Money (Cash) Benefit is covered up to a maximum limit as shown in the Schedule of Benefits for the selected plan.
Back to topCoverage for any individual article, including pairs or sets, is subject to the per-item limit. An Individual Article may include:
- Camera
- Laptop
- Jewelry
Single Article Limit Benefit is covered up to a maximum limit as shown in the Schedule of Benefits for the selected plan.
Back to topWe provide coverage for non-refundable tuition and course fees- should you be forced to cancel or cut your trip short due to a covered event. Reimbursement is limited to the portion of the fees that cannot be recovered from the education provider or institution.
Unused Course Fees Benefit is covered up to a maximum limit as shown in the Schedule of Benefits for the selected plan.
Back to topCancer cover explained
We understand that a cancer diagnosis can be life-changing. That’s why we've included a specific section within the scheme to help you understand the level of cancer treatment cover available.
The scheme provides benefits for eligible outpatient, day case, and inpatient cancer treatment. To ensure you always receive the highest quality care, we work with centres of excellence for cancer treatment. If you are diagnosed with cancer, we may ask you to transfer to one of these centres, which could be in either the private or NHS sector.
If you choose to receive free eligible inpatient, day case or outpatient cancer treatment at an NHS centre, you may be eligible for the NHS cancer cash benefit, as outlined in your healthcare table of benefits.
Our nurse case managers are here to guide you through your cancer treatment and provide information on your available options.
The table below offers a summary of the cancer cover provided. Please read it alongside your healthcare table of benefits for full details.
| Summary of cancer benefits | What’s covered | What’s not covered |
| Where will I be covered to have cancer treatment? |
You will be covered in full for eligible cancer treatment:
|
You will not be covered for:
|
| What diagnostics will I be covered for? |
You will be covered in full for:
|
You will not be covered for any diagnostics that are:
|
| Will I be covered for surgery? |
You will be covered in full for:
|
You will not be covered for surgery that is:
|
|
Will I be covered for preventative diagnostics and treatment? |
You will be covered for prophylactic (preventative) surgery if:
For example, we will pay for a mastectomy to a healthy breast in the event that you have been diagnosed with cancer in the other breast and your specialist indicates that prophylactic surgery is medically necessary and will be carried at the same time as surgery to the diseased breast. You must have our written agreement before you have diagnostics or treatment and we will need full clinical details from your specialist before we can give our decision. |
You will not be covered for any preventative diagnostics or treatment, including:
|
|
What cancer drugs will I be covered for? |
You will be covered in full for:
|
You will not be covered for:
|
| Will I be covered for radiotherapy? |
You will be covered in full for radiotherapy, including when given for pain relief. |
You will not be covered for radiotherapy that is:
|
| Will I be covered for end of life care? |
|
You will not be covered for:
|
|
What cover will be available for routine monitoring when |
You will be covered for follow-up tests and specialist consultations to monitor you once you have completed cancer treatment. No time limits are placed on follow up tests and consultations as long as these are medically necessary and your specialist confirms this in writing. |
|
|
What other benefits and services are available? |
You will be covered for:
Please note, these are subject to any limits as outlined in your healthcare table of benefits |
You will not be covered for:
|
Second medical opinion
If you would like to receive a second medical opinion to feel confident with your specialist's recommendations, please contact us to discuss pre-authorisation. Our experienced claims team is here to guide and support you through the process.
Second opinions will be arranged with a specialist who is an expert in their field and is recognised for providing such consultations.
Please note, without written authorisation, we cannot cover any recommended or resulting diagnostics or treatment from a second opinion.
Virtual GP
As part of your scheme, you have access to a virtual GP service called YourHealth247, provided by Teladoc Health.
You can register for this service via the Member Zone or My Healix app, or directly through their portal at:
http://www.yourhealth247.co.uk/
The portal is the fastest and easiest way to sign up and book your consultations. If you cannot access the portal, you can also call YourHealth247 on 0204 586 5324.
To register, you will need your member number, found in your welcome or renewal email.
If YourHealth247 make an onward referral, we can accept this in place of a referral from your NHS GP, provided that their recommendation is eligible for cover. Contact us to confirm eligibility.
Onward referrals are subject to your scheme underwriting, any personal exclusions (if applicable) and scheme exclusions and limitations. If additional information about your medical history is needed, we may require your consent to contact your NHS GP.
Section 9: Glossary
The words and phrases below have the following meanings. They will appear in bold in this guide.
Acute condition
Annual renewal date
Scheme Benefit, Scheme Benefits
Biological therapies
Cancer
Chronic condition
- requires ongoing or long-term monitoring through consultations, examinations, check-ups and / or tests
- needs ongoing or long-term control or relief of symptoms
- requires rehabilitation or for you to be specially trained to cope with it
- continues indefinitely
- has no known cure, or
- comes back or is likely to come back. <
Complementary practitioner
- Acupuncture practitioners must be registered with the BMAS (British Medical Acupuncture Society), BacC (British Acupuncture Council), AACP (Acupuncture Association of Chartered Physiotherapists) or AAC (The Association of Acupuncture Clinicians)
- Osteopaths must be registered with the GOsC (General Osteopathic Council)
- Chiropractors must be registered with the GCC (General Chiropractic Council)
Day case
Dependant, Dependants
- a employee's unmarried dependant children
Addiction treatment programme
Treatment date
Experimental treatment
- the harmful effects are outweighed by the beneficial effects
- they are likely to lead to the same or better outcomes than available alternatives
- they are based on established medical practice in the United Kingdom <
Private hospital, Private hospitals
NHS hospital, NHS hospitals
Dependant child, Dependant child's, Dependant children, Dependant children's
Emergency repatriation
Primary Care
Sexual and reproductive health services
At Healix, we know it’s vital to receive quick access to healthcare, we have therefore made access for sexual and reproductive health concerns as easy and smooth as possible.
You can contact the claims helpline, and speak to our experienced claims team, they will be able to guide you to the most appropriate services, including access to a remote advice service with one of our in-network experts. This service is self-referred and can be used to discuss any sexual or reproductive health concern, such as the menopause, sexual health, fertility or contraception with an expert specialist in the subject.
The majority of sexual and reproductive health conditions would be covered under your normal outpatient and inpatient benefits, however some conditions would traditionally sit outside the healthcare scheme cover. We have therefore created the additional benefits, to provide some extra cover, if this is required. Our experienced claims team will be able to advise you further on whether your condition and treatment would be covered under these extra benefits.
The below table outlines the services available, and how to access them through your healthcare scheme.
| Health concern | How to access treatment |
|
For advice regarding any sexual or reproductive health query, including, but not limited to, menopause symptoms , urinary symptoms, sexual health or fertility advice |
You can self-refer by contacting the claims helpline, without the need for a GP referral, and we will be able to direct you to the most appropriate service available to you. This includes access to remote consultations and diagnostic tests, with one of our in-network experts (where appropriate). Cover is available up to the limits specified in your table of benefits. Once this benefit limit has been reached, the scheme rules apply as detailed in your exclusions and limitations. |
|
If you are concerned about a breast or testicular abnormality, for example a lump or about early signs of prostate cancer |
Contact the claims helpline to speak to our experienced claims team, who will be able to support you and direct you to the most appropriate specialist, without the need to see your GP first. Cover will be available as specified in your table of benefits. |
|
If your GP has referred you to a specialist |
Contact the claims helpline to speak with our experienced claims team, who will be able to open a new claim and direct you to the most appropriate specialist. Cover will be available as specified in your table of benefits. |
|
If you are experiencing complications of pregnancy |
Contact the claims helpline to speak with our experienced claims team, who will be able to advise if there is any cover available for you. Cover will be available for specific pregnancy complications only, as specified in your exclusions and limitations. |
|
For physiotherapy treatment for a pelvic problem such as stress incontinence |
Contact the claims helpline, without the need for a GP referral, and speak with our experienced claims team who will arrange a telephone based assessment with a senior physiotherapist, to determine the most appropriate treatment for you. Cover is available from your physiotherapy benefit, as specified in your table of benefits. |
Self-referred cancer benefits
Experiencing symptoms that may be associated with cancer can be worrying, but it's important to remember that these symptoms don’t always indicate cancer. We are here to offer prompt support if you experience any symptoms that could potentially be related to cancer.
If you have any of the symptoms listed below, contact us to self-refer for a consultation and diagnostics. There is no need to see your GP these benefits, ensuring no delays in reaching a diagnosis.
Our experienced claims team will guide you through one of our clinical pathways with in-network providers.
| Type of cancer | Signs and symptoms to watch out for |
|
Breast cancer |
|
|
Bowel cancer |
|
|
Prostate cancer |
Raised PSA level as specified below:
|
|
Testicular cancer |
|
|
Skin cancer |
Any of the following changes to a mole or lesion on the skin:
|
Please remember that these symptoms can often be signs of common health issues that are not related to cancer, such as cysts, piles or infection.
If a cancer diagnosis is made, cover will be available as outlined in the cancer cover explained section. One of our nurse case managers will be there to guide you and provide information on options available to you.
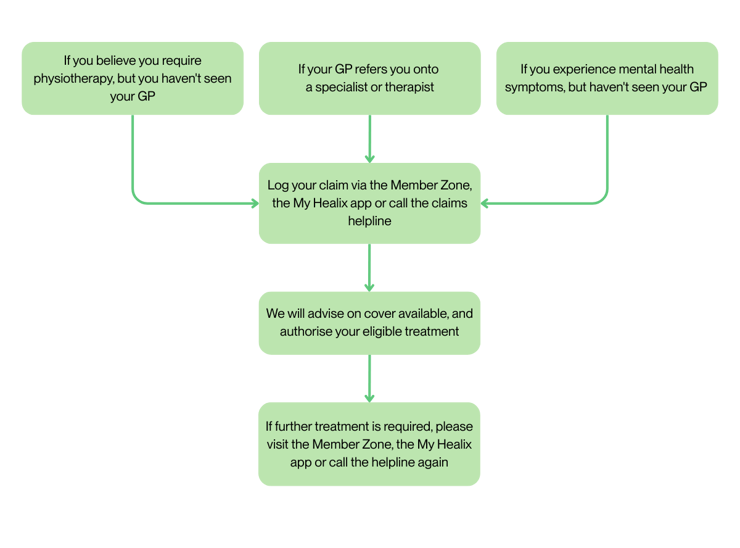
As with all healthcare benefits, it’s essential that you contact us before receiving any consultations, diagnostics or treatment to confirm this is eligible and to avoid incurring any unexpected costs. For further advice, or to open a new claim, you can access the Member Zone, the My Healix app or contact us to speak with our experienced claims team.
Musculoskeletal health pathway
Musculoskeletal conditions affect your muscles, bones and joints. They are very common and tend to increase with age.
Pain and discomfort can affect your daily activities but early diagnosis and treatment may help to ease your symptoms and improve the length of time it takes to recover. We have designed the Healix musculoskeletal pathway with this in mind.
How to make a claim
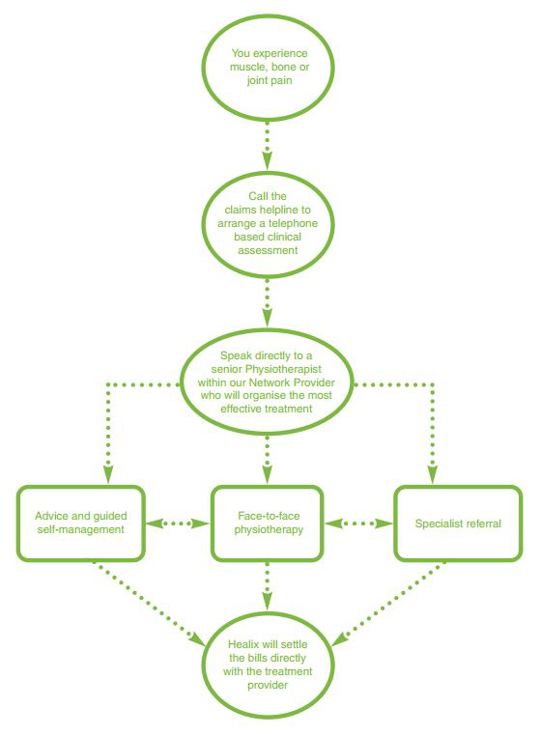
As soon as you experience bone or joint pain you can contact the helpline for support and advice. There is no need to see your GP or obtain a referral letter.
Our experienced team will take your details and arrange for you to have an initial telephone consultation with a senior physiotherapist at a convenient time for you who will recommend the most appropriate treatment pathway.
This could be one of three options:
- face to face physiotherapy with an approved physiotherapist
- guided self-management using a bespoke, evidence-based exercise programme and regular one-to-one calls with a physiotherapist
- referral on to a specialist – we can help locate a specialist at a hospital near you
Musculoskeletal Health Pathway
Mental health pathway
The importance of mental health and wellbeing is becoming increasingly recognised in today’s busy world. Acknowledging stress and anxiety and seeking help are the first steps to developing coping strategies and recovery.
How to make a claim
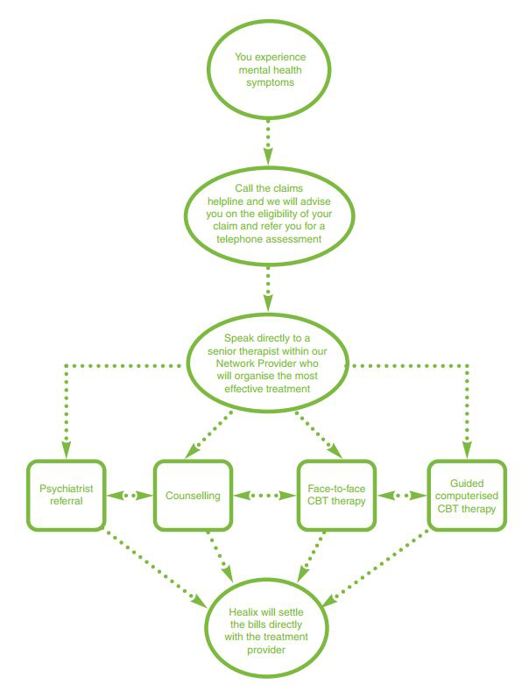
If you are experiencing stress, anxiety or depression or any other mental health problem, you can contact the Helpline for support and advice. There is no need to see your GP or obtain a referral letter.
Our experienced team will take your details and arrange for you to have an initial telephone consultation with a senior psychological therapist at a convenient time for you. This will give you an opportunity to talk through your concerns and agree on the best treatment pathway.
This could be one of several options including:
-
face to face cognitive behavioural therapy (CBT)
-
guided online CBT
-
counselling
-
referral onwards to see a psychiatrist
Healix will pre-authorise your assessment and treatment (within benefit limits where applicable) and settle all invoices directly.
Mental Health Pathway
*Under 18s will require a referral letter from a GP or specialist.
Digital skin pathway
Changes in your skin can be concerning, though most are not cancer-related. Our digital skin pathway ensures rapid assessment and results, with recommendations for further consultations, diagnostics and treatment as needed, depending on your diagnosis. Any subsequent cover will be subject to the healthcare scheme terms and conditions.
This pathway is suitable for a variety of skin conditions, and our experienced claims team can guide you to the most appropriate pathway based on your symptoms.
The table below outlines the skin complaints best suited for referral into our digital skin pathway.
| Skin conditions suitable for the skin pathway | Skin conditions not suitable for the skin pathway |
|
|
How to access the digital skin pathway
Our digital skin pathway is designed to be simple and efficient. Follow the steps below to access fast, expert care:
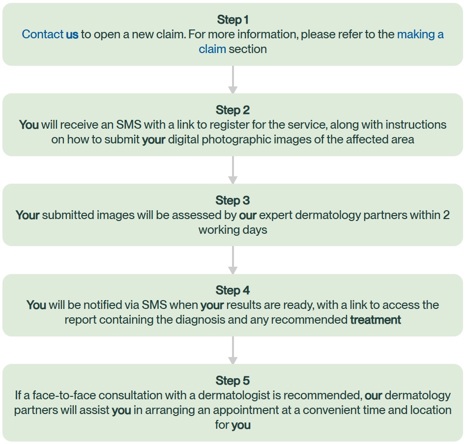
Please note, face-to-face consultations with dermatologists within our network will not be subject to our reasonable and customary fees. If you choose see a specialist outside our network, these fees will apply.
Section 9: Glossary
The words and phrases below have the following meanings. They will appear in bold in this guide.
Acute condition
Annual renewal date
Scheme Benefit, Scheme Benefits
Biological therapies
Cancer
Chronic condition
- requires ongoing or long-term monitoring through consultations, examinations, check-ups and / or tests
- needs ongoing or long-term control or relief of symptoms
- requires rehabilitation or for you to be specially trained to cope with it
- continues indefinitely
- has no known cure, or
- comes back or is likely to come back. <
Complementary practitioner
- Acupuncture practitioners must be registered with the BMAS (British Medical Acupuncture Society), BacC (British Acupuncture Council), AACP (Acupuncture Association of Chartered Physiotherapists) or AAC (The Association of Acupuncture Clinicians)
- Osteopaths must be registered with the GOsC (General Osteopathic Council)
- Chiropractors must be registered with the GCC (General Chiropractic Council)
Day case
Dependant, Dependants
- a employee's unmarried dependant children
Addiction treatment programme
Treatment date
Experimental treatment
- the harmful effects are outweighed by the beneficial effects
- they are likely to lead to the same or better outcomes than available alternatives
- they are based on established medical practice in the United Kingdom <
Private hospital, Private hospitals
NHS hospital, NHS hospitals
Dependant child, Dependant child's, Dependant children, Dependant children's
Emergency repatriation
Primary Care
Making a claim
Healthcare benefits
You can register your claim easily through the Member Zone or the My Healix app. Alternatively, you can contact us to check if your condition or referral is eligible under the terms and conditions of the scheme.
When opening a new claim, we may request a copy of your GP referral letter to allow us to accurately assess your claim.
It's essential that you contact us before receiving any consultations, diagnostics and treatment to confirm it's eligible.
Download the My Healix app
Access the Member Zone
Click here to access the Member Zone
Please note, all members over the age of 16 will need to register for their own account to comply with GDPR requirements. Dependants under the age of 16 will have their details linked to the main members account.
Contact the claims helpline:
0204 615 3441
Monday-Friday 08.00-19.00 (Excl. bank holidays)
We will confirm:
- whether your proposed treatment (including consultations, diagnostics and therapies) is eligible for cover under the scheme.
- whether the costs will be covered.
- any benefit limits or excess that may apply to your claim.
To assist you, we have provided a helpful how to claim summary.
Pay and claim benefits
When submitting a claim for these benefits, you are required to complete a claim form. This can be completed online via the Member Zone or the My Healix app. All reimbursement claims must be submitted within six months of the treatment date.
Refer to the how to claim a reimbursement section, for further information.
How to claim summary
Hospital cover
Open network
The scheme offers an open network, which allows you to attend a hospital of your choice.
For assistance in finding a hospital or specialist, you can use our provider finder.
Please note, our reasonable and customary fees will apply to specialist services.
It is important that you contact us before receiving any consultations, diagnostics or treatment to confirm it's eligible for cover under the scheme.
Reasonable and customary fees
We apply a schedule of reasonable and customary (R&C) fees for charges made by providers, including but not limited to, a specialist, practitioner, physiotherapist, complementary practitioner or a psychological therapist. These fees are aligned with the common codes and principles set out by the Clinical Classification and Schedule Development (CCSD) group. Our fee levels are carefully reviewed, based on what the majority of providers charge for medical and surgical services, and are validated by our clinical support team, and panel of specialist advisors.
If you choose a provider who charges above our fee schedule, you have the option to either pay the difference yourself or we can help identify an alternative provider who charges within the approved fee schedule.
Refer to our fee schedule or contact us for further information.
What happens in an emergency?
Most private hospitals are not equipped for emergency admissions. In the event of an emergency you should:
- call for an NHS ambulance
- visit the accident and emergency (A&E) department at your local NHS hospital
If you wish to be transferred to a private hospital after receiving emergency care, contact us to discuss your options. We will confirm if your proposed treatment is eligible under the scheme.
What is not covered :
- emergency treatment costs at a private walk-in centre, A&E department, or clinic
- costs for intensive care or a high dependency unit if transferred to a private hospital specifically for this care
- transfer costs to a private hospital to receive treatment in an intensive care or high dependency unit
General Provisions and Limitations
Premium Payment Clause
The Insured undertakes that premium due under this policy will be paid monthly to the insurers within 30 days of month end.
If a monthly instalment of premium has not been so paid to the insurers by the date it is due, the insurers shall have the right to cancel this policy by notifying the Insured via the Coverholder in writing. In the event of cancellation, premium is due to the insurers on a pro rata basis for the period that the insurers are on risk but the full policy premium shall be payable to the insurers in the event of a loss or occurrence prior to the date of termination which gives rise to a valid claim under this policy.
It is agreed that the insurers shall give not less than 30 days prior notice of cancellation to the Insured via the Coverholder. If premium due is paid in full to the insurers before the notice period expires, notice of cancellation shall automatically be revoked. If not, the policy shall automatically terminate at the end of the notice period.
Unless otherwise agreed, the Leading Underwriter (and Agreement Parties if appropriate) are authorised to exercise rights under this clause on their own behalf and on behalf of all insurers participating in this contract.
If any provision of this clause is found by any court or administrative body of competent jurisdiction to be invalid or unenforceable, such invalidity or unenforceability will not affect the other provisions of this clause which will remain in full force and effect.
Where the premium is to be paid through a London Market Bureau, payment to the insurers will be deemed to occur on the day of delivery of a premium advice note to the Bureau.
Several Liability Notice
The subscribing insurers' obligations under contracts of insurance to which they subscribe are several and not joint and are limited solely to the extent of their individual subscriptions. The subscribing insurers are not responsible for the subscription of any co-subscribing insurer who for any reason does not satisfy all or part of its obligations.
Pre-approval Requirements
Healix Health must approve in advance any surgery, invasive procedure, major diagnostic testing or major medical treatments, or medical treatment outside of the United Kingdom before any expenses are incurred. It remains your responsibility to contact Healix Assistance for approval or to inform someone on your behalf to do so, except in extreme circumstances where such action would delay surgery required to resolve a life-threatening medical crisis. If such services are not pre-approved then notification must be received within 48 hours otherwise claims will be assessed as per the terms and conditions of the policy, and if approved, reimbursed at 80% of all eligible expenses up to the policy limits and maximum. In some cases, the approval must be provided by us before any expenses are incurred.
Clerical Error
Clerical error on our part or on the part of the plan administrator in the keeping of records for furnishing of information shall not void any insured person’s insurance otherwise validly in force, provided the proper premium remittance is made, nor shall it continue any insured person’s insurance otherwise validly terminated under the terms of the policy.
Applicable Law
This contract of insurance shall be governed by and construed in accordance with English law. The English courts shall have exclusive jurisdiction over any legal proceeding by you, your heirs or assigns.
Other Insurance
Benefits under this policy are payable in excess of those available under any other similar plans or insurance policies, or contracts, or government health insurance plans, or any private, public, or state automobile insurance plan, providing hospital, medical or therapeutic coverage or benefits, or any other third party liability insurance in force. You may not claim or receive in total more than 100% of the loss caused by the insured event.
Limitation of Benefits
Healix Assistance on behalf of the insurers reserves the right, as reasonably required and at its expense, to transfer you to any hospital or your home country following an emergency. If you refuse to be transferred or transported when declared medically fit to travel by the director, any continuing costs incurred after your refusal will not be covered and the payment of such costs becomes your sole responsibility. Coverage ceases upon your refusal and no coverage will be provided to you for the remainder of the coverage period.
Limits on Assistance Services
Healix Assistance reserves the right to suspend, curtail or limit services in any area or country in the event that war, political instability or hostility renders the area inaccessible. Healix Assistance will use its best efforts to provide services during any such occurrence.
Availability and Quality of Care
Neither the insurer nor Healix Assistance shall be responsible for the availability or quality of any medical treatment (including the results thereof) or your failure to obtain medical treatment during the coverage period.
Time limit for recovery of insurance money
Every action or proceeding against the insurers for the recovery of insurance money payable under the contract is absolutely barred unless commenced within the time set out in the laws that apply to this policy.
Refunds
In the event that you have cancelled your trip, you have been denied entry to the United Kingdom, or that you return permanently to your home country, you shall be entitled to a pro-rata refund of the unused portion of the insurance premium you have paid, provided that no claims have been or will be submitted under this policy.
Premiums
This policy is provided for the coverage period, provided that premiums are paid. For subsequent coverage periods a new policy can be purchased, subject to the rate table in effect at the time of the purchase.
1. The Contract
The application, this policy, any document attached to this policy when issued, and any amendment to the policy agreed upon in writing after the policy is issued, constitute the entire policy, and no agent has authority to change the policy or waive any of its provisions.
2. The Waiver
The insurers shall be deemed not to have waived any condition of this policy, either in whole or in part, unless the waiver is clearly expressed in writing signed by the insurers.
3. Copy of Application
The insurers shall, upon request, furnish to the insured or to a claimant under the policy of a copy of the application.
Healthcare policy exclusions
This policy does not cover losses or expenses related in whole or in part, directly or indirectly, to any of the following:
Healthcare policy exclusions
Loss, destruction, or damage directly caused by pressure waves caused by aircraft and other aerial devices travelling at sonic or supersonic speed.
Death or injury sustained while operating or learning to operate any aircraft as pilot or crew.
Any sickness or injury if at the time of the sickness or injury, you are under the influence of drugs, alcohol or other intoxicants (unless administered on, and in strict accordance with, the advice of a legally qualified doctor).
The failure or inability of any equipment or any computer program, whether or not you own it, to recognise or to interpret correctly or process any data as its true calendar date or to continue to function correctly beyond that date.
Any COVID claims arising within 7 days of the date you took out this insurance or the time of booking any trip, whichever is the later, except where insurance is taken out within 48 hours of booking the trip; with the addition of:
-
- Any COVID claims where you have not received a positive COVID diagnosis certified by a medical practitioner; or
- Any home or self-administered COVID rapid antigen test(s).
1.1 Subject only to clause 1.2 below, in no case shall this insurance cover loss damage liability or expense directly or indirectly caused by or contributed to by or arising from the use or operation, as a means for inflicting harm, of any computer, computer system, computer software programme, malicious code, computer virus or process or any other electronic system.
1.2 Where this clause is endorsed on policies covering risks of war, civil war, revolution, rebellion, insurrection, or civil strife arising therefrom, or any hostile act by or against a belligerent power, or terrorism or any person acting from a political motive, Clause 1.1 shall not operate to exclude losses (which would otherwise be covered) arising from the use of any computer, computer system or computer software programme or any other electronic system in the launch and/or guidance system and/or firing mechanism of any weapon or missile.
Any consequences of cyber terrorism including, but not limited to, the delay or cancellation of flights or critical systems.
Any elective, dental, plastic or cosmetic surgery except as the result of a covered emergency, as provided under Dental Benefits.
Any medical treatment claimed under the Emergency Benefits section of the policy which can reasonably be delayed until you return to your home country by the next available means of transportation, whether you intend to or not.
Drugs and medications which are: a. commonly available without a prescription, preventative medications or vaccines (except as provided under Vaccinations and Tuberculosis Testing), acne medications, baldness remedies, nicotine resin products, dietary supplements or weight loss products; b. any type of contraceptive (except as provided under Maternity Benefit), pregnancy test, fertility drug or test, or erectile dysfunction drugs; c. not legally registered and approved in the United Kingdom or not medically necessary.
The worsening, recurrence, side effects or complications of a medical condition resulting from your non-compliance or failure to follow the directions of a doctor or other health care provider.
Further medical treatments or services in the United Kingdom for any sickness, injury, or medical condition that arose during a visit to your home country, except where travel is expressly taken in order to participate in an educational institution organised sporting or extra-curricular event.
A sickness or injury that, at the time of departure from your home country, might reasonably be expected to require you to undergo medical treatment, surgery or hospitalisation.
Injury resulting from participation in: professional athletics (for which you are remunerated); mountain climbing; remote country rock climbing; aviation except as a fare-paying passenger on a commercial aircraft; hang gliding; sky diving; parachuting; bungee jumping; remote country downhill skiing/snowboarding; motorised speed events or contests; scuba diving unless PADI/NAUI certified or accompanied by a certified instructor.
Any sickness, injury or medical condition resulting from your commission or attempted commission of an illegal act.
Injuries received while you are participating in any manoeuvres or training exercises of the armed forces, national guard or organised reserve corps of any country or international authority.
Any consultation or treatment for attention deficit hyperactivity disorder (ADHD) or similar conditions or diagnoses.
Any medical treatment claimed under the Emergency Benefits section of the policy that is not emergency medical treatment for the immediate relief of acute pain and suffering.
Any medical treatment claimed under the Emergency Benefits section of the policy which can reasonably be delayed until you return to your home country by the next available means of transportation, whether you intend to or not.
It is agreed that, regardless of any contributory cause(s), this insurance does not cover any claim(s) in any way caused or contributed to by an act of terrorism involving the use or release or the threat thereof of any nuclear weapon or device or chemical or biological agent.
For the purpose of this exclusion an act of terrorism means an act, including but not limited to the use of force or violence and/or the threat thereof, of any person or group(s) of persons, whether acting alone or on behalf of or in connection with any organisation(s) or government(s), committed for political, religious, ideological or ethnic purposes or reasons including the intention to influence any government and/or to put the public, or any section of the public, in fear.
If the Underwriters allege that by reason of this exclusion any claim is not covered by this insurance the burden of proving the contrary shall be upon the Assured.
Claims or losses arising directly or indirectly from any pandemic or epidemic unless specifically listed by this policy.
Pregnancy, miscarriage, voluntary termination of pregnancy, childbirth, or their complications except as otherwise provided in Maternity Benefit.
Radioactive contamination. This policy excludes any claim directly or indirectly consequent upon or contributed by:
a) Ionising radiation or contamination by radioactivity from any nuclear fuel or from any nuclear waste from the combustion of nuclear fuel,
b) Radioactive toxic explosion or other hazardous properties of any explosion, nuclear assembly, or nuclear component thereof, howsoever such release or explosion is caused.
Suicide or any attempt at suicide, or intentionally self-inflicted injury whether you are sane or insane
Medical examinations performed at the request of a third party (including medical examinations for immigration purposes).
Transplants including, but not limited to, cornea or organ transplants or bone marrow transplants, artificial joints, prosthetic devices or implants including any associated charges.
Any sickness, injury or medical condition for which a diagnosis need not have been made, where the policy is purchased or the visit is undertaken for the purpose of securing or with the intent of receiving medical or hospital services, whether or not such visit is taken on the advice of a doctor or surgeon.
Travel to, from or through any country, region or city for which, prior to the effective date or your departure date, any department of the United Kingdom Government has issued a warning to avoid all travel or to avoid non-essential travel, if the expenses are the result of the reason for which the warning was issued.
Any costs incurred due to your travelling against the advice of a doctor or any loss resulting from your sickness or medical condition that was diagnosed by a doctor as a terminal illness prior to the effective date.
Medical treatment or services normally covered or reimbursable under any other insurance.
Medical treatments or services within your home country except where travel is expressly taken in order to participate in an educational institution organised sporting or extra-curricular event.
Any sickness, injury or medical condition that was not stable in the 90 days prior to the effective date.
Any virtual currency including, but not limited to, crypto currency, including fluctuations in value.
Any claim arising as a result of you failing to obtain, hold, produce, or maintain the required immigration, work, residence or similar visas, permits, or documents for the country to which you are traveling.
War and Terrosism notwithstanding any provision to the contrary within this insurance or any endorsement thereto it is agreed that this insurance excludes loss, damage, cost or expense of whatsoever nature directly or indirectly caused by, resulting from or in connection with any of the following regardless of any other cause or event contributing concurrently or in any other sequence to the loss;
War, invasion, acts of foreign enemies, hostilities or warlike operations (whether war be declared or not), civil war, rebellion, revolution, insurrection, civil commotion assuming the proportions of or amounting to an uprising, military or usurped power; or any act of terrorism.
For the purpose of this endorsement an act of terrorism means an act, including but not limited to the use of force or violence and/or the threat thereof, of any person or group(s) of persons, whether acting alone or on behalf of or in connection with any organisation(s) or government(s), committed for political, religious, ideological or similar purposes including the intention to influence any government and/or to put the public, or any section of the public, in fear.
This endorsement also excludes loss, damage, cost or expense of whatsoever nature directly or indirectly caused by, resulting from or in connection with any action taken in controlling, preventing, suppressing or in any way relating to one (1) and/or two (2) above.
If the Underwriters allege that by reason of this exclusion, any loss, damage, cost or expense is not covered by this insurance the burden of proving the contrary shall be upon the assured.
In the event any portion of this endorsement is found to be invalid or unenforceable, the remainder shall remain in full force and effect.
An act of declared or undeclared war, civil war, rebellion, revolution, insurrection, military or usurped power or confiscation or nationalization or requisition by or under the order of any government or public or local authority.
Reimbursement policy exclusions
The following are conditions and treatments which are not covered under your scheme. If you are unsure about anything in this section, please contact us on the claims helpline.
Exclusions and limitations
Sickness, disease, or disability whether the loss or claim results directly or indirectly from any of these:
- Mental incapacity whether the loss or claim results directly or indirectly from any mental incapacity.
- Sustained while you are undergoing the medical or surgical treatment of sickness, disease, or bodily or mental infirmity.
- Stroke or cerebrovascular condition, cardiovascular condition including, but not limited to, myocardial infarction or heart attack, coronary thrombosis, aneurysm.
- Travel or flight in or on (including getting in or out of, or on or off of) any vehicle used for aerial navigation, if you are:
- Riding as a passenger in any aircraft not intended or licensed for the transportation of passengers; or
- Performing, learning to perform, or instructing others to perform as a pilot or crew member of any aircraft.
- Infection of any kind regardless of how contracted, except bacterial infection that are directly caused by botulism, ptomaine poisoning or an accidental cut or wound independent and in the absence of any underlying sickness, disease or condition including but not limited to diabetes.
- An act, attempted act or omission taken or made by you, or an act, attempted act or omission taken or made with your consent, for the purpose of interruption the blood flow to your brain or to cause asphyxiation to you, whether with intent to cause harm or not.
- Natural causes.
- Any claim resulting from:
- Claims which do not relate to your trip.
- Claims due to delay, confiscation or detention by customs or other authority; or
- Claims arising from baggage shipped as freight or under a bill of lading.
- Any costs or charges for which any carrier or provider must, has or will compensate you.
- Any claim resulting from:
- Reimbursement for items purchased after your baggage was returned.
- Reimbursement where itemised receipts are not provided; or
- Reimbursement for any purchases made after 4 days of your arrival at your destination.
- Anything mentioned in the general exclusions section.
- Any claim resulting from:
a. Loss or theft of or damage to valuables, personal money, passport or travel documents left unattended at any time (including in a vehicle or while in the care of a carrier), unless they were in a locked hotel safe or locked safety deposit box or left in your locked (doors and all windows) accommodation.
b. Loss or theft of, or damage to, baggage in an unattended motor vehicle between 9pm and 9am (local time) or baggage in an unattended motor vehicle between 9am and 9pm (local time), unless it is in the locked boot, which is separate from the passenger compartment or, for those vehicles without a separate boot, locked in the vehicle and covered from view.
c. Claims arising from loss or theft from your accommodation unless there is evidence of forced entry which is confirmed by a police report; or
d. Loss or damage due to your baggage, valuables, personal money, passport or travel documents being delayed, confiscated or detained by customs or any other authority.
- Any claim resulting from:
a. Claims which are not supported by the proof of ownership or insurance valuation (obtained prior to the loss) of the item(s) lost, stolen or damaged; or
b. Damaged items damaged whilst you are on a trip when you do not obtain a damage/repair statement from an appropriate agent within 7 days of your return to your country of temporary residence.
- Any claim resulting from:
a. Cheques, traveller’s cheques, postal or money orders, pre-paid cards, coupons or vouchers, travel tickets, event and entertainment tickets, phone cards and credit, debit or charge cards if you have not kept to the issuer’s conditions or if the issuer provides a replacement service.
b. Claims relating to currency when you do not produce evidence of the withdrawal; or
c. Loss or damage due to loss in value, variations in exchange rates or shortages due to an error or due to fraudulent or attempted fraudulent use of credit cards.
- Claims arising from:
a. Damage caused by leakage of powder or liquid carried within baggage.
b. Baggage shipped as shipped as freight or under a bill of lading.
c. Damage caused by wear and tear, depreciation, deterioration, atmospheric or climatic conditions, moths, vermin, any process of cleaning repairing or restoring, mechanical or electrical breakdown or liquid damage.
d. Loss or damage due to breakage of sports equipment or damage to sports clothing whilst in use; or
e. Items used in connection with your business, trade, profession or occupation.
- Any amounts already paid under Baggage Delay Benefit.
Anything mentioned in the general exclusions section.
- Any claim resulting from:
a. Costs or charges for which any carrier or provider must, has or will reimburse you and any amounts paid in compensation by the carrier.
b. Costs where you have not checked in or attempted to check in according to the itinerary supplied to you.
- Any claim resulting from:
a. Strike or industrial action or air traffic control delay existing or publicly declared by the purchase date of this insurance or at the time of booking your trip (whichever is the earlier).
b. Withdrawal from service (temporary or otherwise) of public transport on the recommendation of the Aviation Authority or a Port Authority or any similar body in any country.
- Any claim resulting from:
a. Any delay of a domestic flight, connecting flight or privately chartered flight.
b. A missed departure or a late arrival at your destination.
c. A cancelled flight (even if this flight is cancelled before its scheduled departure time as per your travel itinerary).
- Any claim where you have not been delayed for more than 12 hours of the scheduled departure time.
- Any delay that occurs that is not your international outbound trip or international inbound trip.
Holidays
- Any claim resulting from:
a. Claims which do not relate to your trip.
b. Extra expenses where the scheduled public transport operator has offered reasonable alternative travel arrangements.
c. Costs more than the original provider’s alternative arrangements for expenses incurred where you take alternative transportation.
d. Expenses when reasonable alternative travel arrangements have been made available by the public transport operator within 12 hours of the actual departure time or actual connecting flight time; or
e. All amounts paid in compensation by the carrier.
- Any claim resulting from:
a. Breakdown of any vehicle in which you are travelling if the vehicle is owned by you and has not been serviced properly and maintained in accordance with the manufacturer’s instructions.
b. Claims where you have not obtained a written report from the police or emergency service, or a repairer’s report and/or receipt within 7 days of you returning home if the vehicle you are travelling in breaks down or is involved in an accident; or
c. Withdrawal from service (temporary or otherwise) of public transport on the recommendation of the Aviation Authority or a Port Authority or any similar body in any country.
- Privately chartered flights.
- Claims where you have not retained and provided original receipts for costs
- Anything mentioned in the general exclusions section.
Any claims arising directly or indirectly from the following:
1. Any liability to or arising from bodily injury, death, serious illness to any person who is:
a. Under a contract of service with you when such injury arises out of and in the course of their employment by you.
b. Your close relative or immedicate family
2. Any liability relating to or arising from loss of or damage to property that belongs to you, or is in the care, custody or control of you, a close relative, travelling companion, anyone in your employment or any member of your household. However, this exclusion shall not apply in respect of loss of or damage to buildings and their contents not belonging to but temporarily occupied by a you in the course of the trip.
3. Compensation or legal costs arising directly or indirectly from:
a. Ownership or occupation of land or buildings (other than occupation only of any temporary trip accommodation).
b. Pursuit of or you carrying out any employment, business, trade, profession or occupation or the supply of goods or services.
c. Ownership, possession or use of mechanically propelled vehicles, automobile, aircraft, watercraft (other than surfboards or manually propelled rowboats, punts, or canoes) or any mechanically propelled conveyance.
d. Activities or volunteer work organised by, or under the auspices of, a charitable, voluntary, not for profit, social or similar organisation when liability for such activities or work should reasonably be included within the organisation’s own public liability policy.
e. The transmission of any communicable disease or virus.
f. Destruction or damage by vandalism, wilful or malicious acts by you, a close relative, or immediate family anyone in your employment or any member of your household or by any person legally entitled to be in or on the rented property.
4. Any claims arising directly or indirectly from COVID.
5. Any liability:
a. Assumed by you under agreement, unless the liability would have attached in the absence of such agreement.
b. Arising out of actions between insured persons.
6. We will not pay for any accidental loss of or damage to property claims under “Personal Liability” section above, of the policy points b, and c and for:
a. Any claims arising directly or indirectly from the following:
i. The cost of repairing or restoring any undamaged part of the property.
ii. Loss or damage caused by pets or domestic animals, for example, damage by chewing, scratching, tearing or fouling by domestic animals.
iii. Loss or damage caused by carrying out structural improvements or alterations.
iv. Loss or damage which happens during any period when the property is unfurnished or unoccupied for more than 30 days in a row; or
v. Loss of or damage to your personal possessions by a close relative, immediate family or anyone in your employment.
b. Matching sets and suites:
i. The cost of replacing any undamaged items that form part of a collection, set or suite, or are part of a common design. for example, if there is damage to floor coverings, we will only payforthe cost of replacing the damaged part or, if we cannot find a matching part, the floor covering in the room where the damage happened and not undamaged floor coverings in other rooms or areas.
c. Mechanical/Electrical Breakdown:
i. Caused by mechanical or electrical breakdown; or
ii. Caused by the use of faulty or unsuitable materials/design, or faulty workmanship.
d. Wear and Tear:
i. By wear and tear, rust, atmospheric or climatic conditions, movement, settlement or shrinkage, wet or dry rot, vermin, insects, fungus, electrical or mechanical breakdown or anything which happens gradually; or
ii. The cost of general maintenance.
e. Escape of Water:
i. To tiles, walls, floors and ceilings caused by the gradual leakage or seepage of water from all fixed sanitary ware units including baths and shower units; or
ii. Caused by water leaking from shower units and baths through seals and grouting.
f. Deliberate or existing damage:
i. Caused by any deliberate act by you, anyone in your employment (for example, a cleaner) or any member of your household or any other person living in the property; or
ii. Which happened before or as a result of an event which happened before this cover started.
We will not reimburse any treatment arising from deliberate self-inflicted injury.
1. Any claims arising directly or indirectly from:
a. Circumstances known to you before the purchase date of your policy or at the time of booking any trip or starting your trip (whichever is later) and which could reasonably have been expected to result in you cutting your trip short.
b. Any claim where you do not get pre-authorization prior to curtailment of your trip.
2. The cost of airport departure duty, taxes and fees.
3. Any costs paid for using any airline mileage reward scheme, for example Avios, or any card bonus point schemes, any timeshare, holiday property bond or other holiday point's scheme and/or any associated maintenance fees.
4. Any unused or additional costs incurred by you which are recoverable from:
a. The providers of the accommodation, their booking agents, travel agent or compensation scheme;
b. The providers of the transportation, their booking agents, travel agent or compensation scheme; your credit or debit card provider or PayPal; or
c. Any other insurance under which you are entitled to indemnity, including any amounts recoverable from any other source.
5. Any claim resulting from:
a. The failure of the provider of any service forming part of your booked trip to provide any part of your booked trip (apart from excursions) including error, insolvency, omission or default; or
b. Any curtailment caused by work commitment or amendment of your annual leave/vacation entitlement by your employer.
6. Claims where you have not complied with the terms of contract of the booking agent, travel agency, tour operator or provider of transport
7. Any claim resulting from your inability to travel due to failure to hold, obtain or produce a valid passport, visa, inoculation certificates, travel tickets and so on, that you need to travel.
8. Claims for travelling companions if they are not insured persons.
9. You do not want to travel, for any reason.
10. Holidays.
11. Anything mentioned in the general exclusions section
Section 9: Glossary
The words and phrases below have the following meanings. They will appear in bold in this guide.
Acute condition
Annual renewal date
Scheme Benefit, Scheme Benefits
Biological therapies
Cancer
Chronic condition
- requires ongoing or long-term monitoring through consultations, examinations, check-ups and / or tests
- needs ongoing or long-term control or relief of symptoms
- requires rehabilitation or for you to be specially trained to cope with it
- continues indefinitely
- has no known cure, or
- comes back or is likely to come back. <
Complementary practitioner
- Acupuncture practitioners must be registered with the BMAS (British Medical Acupuncture Society), BacC (British Acupuncture Council), AACP (Acupuncture Association of Chartered Physiotherapists) or AAC (The Association of Acupuncture Clinicians)
- Osteopaths must be registered with the GOsC (General Osteopathic Council)
- Chiropractors must be registered with the GCC (General Chiropractic Council)
Day case
Dependant, Dependants
- a employee's unmarried dependant children
Addiction treatment programme
Treatment date
Experimental treatment
- the harmful effects are outweighed by the beneficial effects
- they are likely to lead to the same or better outcomes than available alternatives
- they are based on established medical practice in the United Kingdom <
Private hospital, Private hospitals
NHS hospital, NHS hospitals
Dependant child, Dependant child's, Dependant children, Dependant children's
Emergency repatriation
Primary Care
Eligibility
Sanction and limitation clause.
No insurer shall be deemed to provide cover and no insurer shall be liable to pay any claim or provide any benefit hereunder to the extent that the provision of such cover, payment of such claim or provision of such benefit would expose that insurer to any sanction, prohibition or restriction under United Nations resolutions or the trade and economic sanctions, laws or regulation of the European Union, United Kingdom or United States of America.
Termination of policy
Travel from your home country to the United Kingdom is covered (including any layover location en route to the United Kingdom) provided the total trip length between departure from your home country and arrival in the United Kingdom does not exceed seven (7) days.
This policy terminates on the earliest of:
- the expiry date indicated in your coverage document;
- the date the required premium is due and unpaid, in accordance with the Premium Payment Clause included in this policy;
- the date you attain age 65;
- the date you permanently return to your home country;
- 60 days after the date you no longer meet the eligibility requirements under Eligibility below (not applicable if you graduate from the educational institution).
Eligibility
To be eligible for coverage, you must be:
- an international student or participant at an educational institution with a current passport and/or student visa, under the age of 65, residing in the United Kingdom, whose name is on file with the plan administrator as being insured under this policy during the coverage period; or
- an international faculty member, teacher, or other affiliate in an educational, business or cultural exchange with an educational institution, under the age of 65, residing in the United Kingdom, whose name is on file with the plan administrator as being insured under this policy during the coverage period; or
- the parent or legal guardian, spouse and/or dependent child(ren) under the age of 65 of any of the persons listed above, residing together in the United Kingdom, and sharing the same coverage period.
Coverage commences on the latest of:
- the date the plan administrator confirms that you are insured under the policy.
- the date that you leave your home country to come to the United Kingdom.
- the effective date shown on your coverage document.
Information you give us
You must take reasonable care when providing information to us. We will rely on information you give us when deciding whether to cover you and on what terms. If any information is untrue, incomplete and/or inaccurate, it may affect your cover.
a. if you carelessly give us incorrect information we can:
i. treat the policy as if it never existed. This means we will not cover any claim, but we will return the premium to you. We will only do this if we would not have entered into the policy if you had given correct information; or
ii. change the terms of the policy with effect from the start of the coverage period. This could include adding additional exclusions or obligations or amending the benefit amounts. We will only do this if we would have applied those other terms if you had given correct information; and/ or
iii. charge an additional premium or reduce the amount we pay for a claim. If we pay for a claim. If we reduce the amount we pay we will do so in proportion to the premium you paid us and the premium we would have charged you. We will only do this if we would have charged a higher premium if you had given correct information;
iv. cancel the policy; or
v. co-operate with the Police and support a prosecution in the event of any criminal behaviour in respect of this policy, such as faking an injury in order to traudulently claim benefits under this policy.
b. if we establish that you deliberately or recklessly provided us with false or misleading information, we will:
i. treat this policy as if it never existed; and
ii. decline all claims; and
iii. co-operate with the Police and support a prosecution in the event of any criminal behaviour in respect of this policy.
You must tell us as soon as possible if you realise you have given us any incorrect information or any information you have given us has changed. When we are told about any such changes, we will let you know if it changes the policy. When we are told about any such change, we will let you know if it changes the policy. We can change policy terms, charge an additional premium or cancel the policy.
If you do not tell us about a change or give us incorrect information when telling us about a change, we may treat the policy as if it never existed, reduce the amount we pay for a claim or decline to pay a claim.
Outside of Country Travel
Educational institution breaks and travel outside the United Kingdom during the coverage period are valid provided at least 51% of the coverage period is spent in the United Kingdom. Coverage to travel to the United States of America is limited to a maximum of 30 days per visit and cannot exceed 49% of the coverage period.
Extended Coverage After Termination Date
If you are hospitalised on the last day of the coverage period for an eligible sickness or injury coverage will be automatically extended until discharge up to a maximum of 30 days without additional premium. Coverage for the same sickness or injury for which you were initially hospitalised will be extended for an additional 72 hours after you are discharged from the hospital to facilitate your return to your home country.
Coverage is automatically extended for up to 72 hours in the event you missed your scheduled return to your home country due to a delay caused by the common carrier in which you are a passenger.
Continuation option
As Healix only provides corporate group schemes, we are unable to continue your cover as an individual if you leave the StudyInsured Scheme.
We understand the importance of your healthcare and choosing a new provider may be daunting. We work closely with two providers to offer you the best choice possible to take your healthcare forward.
What is a continuation option?
A continuation option allows members who resign or retire from an employer that provides workplace healthcare benefits, to take out their own cover. You might be eligible to take over the benefits previously paid for by the employer, however it’s not always guaranteed that any ongoing claims will be covered.
National Friendly
Who are NF?
A Friendly Society that helps its customers meet their health protection needs by offering you cover through private medical insurance policies.
How do I contact them?
Call 0333 014 6244, (8am-6pm Monday to Friday). Quote HEALIX and the team will be able to obtain the best possible terms for your transition.
What do they cover?
My Private Medical Insurance policy is a flexible product that offers cover for everyone up to age 85. You can choose between guided outpatient only cover all the way through to unlimited inpatient cover.
To find out more about National Friendly visit here.
Usay Compare
Who are Usay?
The largest individual health insurance intermediary and are experts at finding the best cover for you.
How do I contact them?
Call 01285 864670 and quote HEALIX.
What do they cover?
Usay Compare will get to know your unique individual requirements, do all the hard work comparing prices and policies for you; then advise on the best and most cost-effective quote.
To find out more about Usay Compare, fill in this online form.
These terms are offered to you as a previous member of the scheme and are available for a limited time only, usually no more than 30 days from the date of leaving. It is therefore important that you act quickly to maintain continuity of cover.
Healix Health Services Ltd is an introducer appointed representative of both National Friendly and Usay Business Ltd, who are authorised and regulated by the Financial Conduct Authority. Calls may be recorded or monitored for quality control.
How to make a complaint
Our aim is to ensure that all aspects of your insurance are dealt with promptly, efficiently and fairly. At all times we are committed to providing you with the highest standard of service
If you wish to make a complaint, you can do so at any time by referring the matter to either MSH or the Complaints team and Lloyd's.
The address of Healix is:
Healix Health Services, Healix House, Esher Green,
Esher, Surrey KT10 8AB
Telephone: 0204 -615 -3441 or 0204- 615- 3441 (when dialling from outside the UK)
Email: studyinsured@healix.com
The address of the Compalints team at Lloyd's is:
Lloyd’s Complaints
Fidentia House, Walter Burke Way
Chatham Maritime
Kent
ME4 4RN
Website: www.lloyds.com/complaints
Telephone: 0207 327 5693
Email: complaints@lloyds.com
Details of Llyod's complaint procedures are set out online at www.lloyds.com/complaints and are also available from the above address.
If you remain dissatisfied after Lloyd’s has considered your complaint, you may have the right to refer your complaint to the Financial Ombudsman Service (FOS)
The contact details for the FOS are:
The Financial Ombudsman Service
Exchange Tower
London
E14 9SR
Telephone: 0800- 023- 4567
Email: complaint.info@financial-ombudsman.org.uk.
The FOS is an independent service in the UK for settling disputes between consumers and businesses providing financial services. You can find more information on the FOS on their website at www.financial-ombudsman.org.uk.
How to claim reimbursement
How to claim for cash benefits
If you have received treatment free of charge on the NHS, you may be eligible to reimbursement of cash benefits as outlined in your reimbursement table of benefits.
These benefits will only be eligible if the treatment received would otherwise have been covered under the scheme.
Please note, only one cash benefit reimbursement can be claimed per admission.
In order to claim these benefits, you must register your claim via the Member Zone or the My Healix app.
You will need to provide the following information for a claim to be processed:
- a copy of your NHS discharge paperwork which should confirm the following information:
- date of admission and discharge from the NHS hospital
- name and date of birth of the person admitted
- summary of the reason for admission and the treatment received
- bank details for the reimbursement to be made to:
- account holder’s name
- sort code
- account number
How to claim reimbursement of medical expenses
If you have paid your treating provider directly for eligible treatment (including consultations, diagnostics and therapies), you can claim reimbursement for these costs as long as it is eligible for cover as outlined in your reimbursement table of benefits.
In order to claim these benefits, you must register your claim via the Member Zone or the My Healix app.
You will need to provide the following information for a claim to be processed:
- an itemised receipt confirming the following information:
- your treatment date
- details of the treatment (including consultations, diagnostics and therapies) received
- amount paid
- bank details for the reimbursement to be made to
- account holder’s name
- sort code
- account number
Important to note:
Once the claim has been confirmed as eligible, reimbursement will be arranged via direct bank transfer.
All reimbursement claims (including cash benefits) must be submitted within six months of your treatment date or birth date.
Additional information can be found in the payment of invoices section.
Notice and proof of claim
Notice and Proof of Claim
You, or a beneficiary entitled to make a claim, or the agent of any of them, shall,
a. Give written notice of claim to the Insurer,
i. By delivery thereof, or by sending it by registered mail to the head office or chief agency of the Insurer in the UK to:
The Lloyd’s Building
One Lime Street
London EC3M 7HA UK
Phone Number: +44 (0)20 7327 1000
or
ii. By delivery thereof to an authorized agent of the Insurer.
not later than 30 days from the date a claim arises under contract on account of an accident, sickness, or disability:
- Within 90 days after the date a claim arises under the contract on account of an accident or sickness, furnish to the insurer such proof as is reasonably possible in the circumstances of:
i. The happening of the accident or the start of the sickness,
ii. The loss caused by the accident or sickness,
iii. The right of the claimant to receive payment,
iv. The claimant’s age, and
v. If relevant, the beneficiary’s age; and
if so, required by the insurer, furnish a satisfactory certificate as to the cause or nature of the accident, sickness or disability for which claim may be made under the contract and as to the duration of sickness or disability.
Failure to Give Notice or Proof
Failure to give notice of claim or furnish proof of claim within the time required by this condition does not invalidate the claim if:
a. The notice or proof is given or furnished as soon as reasonably possible, and in no event later than 1 year after the date of the accident or the date a claim arises under the contract on account of sickness or disability, and it is shown that it was not reasonably possible to give the notice or furnish the proof in the time required by this condition, or
b. In the case of death of the person insured, if a declaration of presumption of death is necessary, the notice or proof is given or furnished no later than one year from the date a court makes the declaration.
Insurer to Furnish Forms for Proof of Claim
The Insurer shall furnish forms for proof of claim within fifteen (15) days after receiving notice of claim, but where the claimant has not received the forms within that time the claimant may submit his proof of claim in the form of a written statement of the cause or nature of the Accident, Sickness or Disability giving rise to the claim and of the extent of the loss.
Rights of Examination
As a condition precedent to recovery of insurance moneys under the contract.
a. The claimant shall afford to the insurer an opportunity to examine them when and so often as it reasonably requires while the claim hereunder is pending; and
b. In the case of death of the person insured, the Insurer may require an autopsy subject to any law of the applicable jurisdiction relating to autopsies.
4 When Money Payable
All money payable under this contract shall be paid by the insurers within 60 days after they has received proof of claim.
Requests for additional information
We may ask you to provide information to help us assess your claim. For example we may ask you for one or more of the following:
-
medical reports and other information about the condition / treatment (including consultations, diagnostics and therapies) you are claiming for. If we request a medical report from your specialist, and they charge for providing this, we will pay the cost
-
original accounts and invoices in connection with your claim
-
an independent medical examination or second opinion with an alternative specialist, and the results of this. We will pay for the cost of any independent medical examination or second opinion we require and we will authorise this in writing, in advance
-
results of any second opinions provided by alternative specialist you have independently sought. On such occasions, we may also request our own, independent, second opinion from an expert in that field. We will pay the costs of any second opinion we request, this includes the cost of the consultation and any diagnostics undertaken as a result of that consultation
We will liaise with you and your specialist throughout your claim, and will request medical information when we deem this to be necessary for assessment of your claim. You will be asked for your consent before we do this.
Throughout your claim, we will make you aware of the options that are available to you. If your specialist recommends treatment (including further consultations, diagnostics and therapies), you should contact us as soon as possible to be sure this is eligible for cover.
Our experienced claims team will assess the level of cover available to you within the terms and conditions of the scheme. In some instances it may be necessary to refer your claim to our specialist nurses, along with our panel of independent specialist advisors, who will advise on the level of cover available.
Healix privacy notice
If you would like to know more about how Healix store and process your personal data, please find our Privacy Notice here.
Definitions
The following are definitions used within your scheme. If you are unsure about anything in this section, please contact us on the claims helpline.
Defintions
Accident means an unexpected and unintentional event exclusively attributable to an external cause resulting in injury.
Baggage and Personal Effects means luggage, clothing and personal belongings which belong to you (or for which you are legally responsible) which you wear, use or carry during a trip. It does not include valuables, golf equipment, personal money and documents of any kind. For baggage claims, we pay the purchase price, less a deduction for a loss in value due to wear and tear. So, this cover is not on a ‘new for old’ basis and we will make a deduction per item when assessing your claim.
If you are planning to take expensive items such as jewellery, gadgets, photographic or telecommunications equipment or other items that we define as valuables on your trip, you should check that you have enough cover for these items under an alternative insurance policy, for example a home contents insurance policy. Please note that there is no cover for items that are more than five years old on the date you start your trip.
Benefits means any covered expenses/services that the insurers will pay under this policy.
Chronic condition means a sickness, disease or injury that is persistent, incurable and does not spontaneously disappear with time.
Claim Documents means the information relevant to your visit to a medical facility. This includes, but is not limited to, a signed claim form, medical notes/records, referrals, itemised bills, payment receipts and prescription receipts.
Common Carrier means any person or company who publicly undertakes to transport passengers by land, water or air on regular routes at agreed rates. Common carriers include railways, ships, airlines, buses and taxis where passengers are charged a fare.
Coverage Document means the certificate that is provided to you either in hard copy or electronically that includes such things as your name, policy number, elected benefits and coverage period.
COVID means coronavirus disease (COVID-19), severe acute respiratory syndrome coronavirus 2 (SARS-CoV-2), or any mutation or variation of these.
Dentist means a practitioner of dentistry lawfully qualified and licensed to practice in the jurisdiction in which they have provided the services or supplies for which the charges are incurred.
Dependent Child(ren) means unmarried persons residing with you and dependent on you for support if you are their parent or legal guardian, and who are:
- at least 15 days old, unless the child is born as a result of an eligible pregnancy as set out under this policy, and under 21 years of age; or
- under 26 years of age and in attendance at an institution of higher education, or
- of any age over 15 days old and have a mental or physical impairment.
Doctor or Surgeon means a medical doctor, other than you or an immediate family member, who is licensed to practice and registered to administer medical treatment and prescribe drugs in the jurisdiction where they provide medical services.
Educational Institution means a school, college, university, or other recognised institution of education in the United Kingdom which has been fully accredited (if required) in accordance with applicable law and regulations.
Emergency means an unexpected sickness or injury which makes it necessary to receive immediate medical treatment for the relief of acute pain or suffering, which cannot be delayed until you return to your home country.
Epidemic or Pandemic means any event(s) declared as an epidemic or pandemic by the World Health Organization or by a relevant national government body.
Excursion means any continuous travel outside of the United Kingdom (and not to your home country) during the coverage period, provided that at least 51% of the coverage period is spent in the United Kingdom.
Fit to Travel means the treating medical practitioner has determined you are able to complete travel to your home country and/or resident country with or without medical attention and services.
Home Country means the country where you maintained a permanent residence prior to entry into the United Kingdom.
Hospital means a healthcare facility which:
• holds a license as a hospital (if licensing is required in the jurisdiction);
• operates primarily for the reception, care and treatment of sick, ailing or injured persons as in-patients;
• provides 24 hour a day nursing service by registered or graduate nurses;
• has a staff of one or more doctors available at all times;
• provides organised facilities for diagnosis and major medical surgical facilities;
• is not primarily a clinic, nursing, rest or convalescent home or similar establishment; and
• is not, other than incidentally, a place for the treatment of alcohol or drug addiction.
Hospitalisation or Hospitalised means you occupy a hospital bed for more than 24 hours for medical treatment and for which admission was recommended by a doctor when medically necessary.
Immediate Family Member means your spouse, parent or legal guardian (including a step-parent), brother or sister (including a step-brother or step-sister), child (including a legally adopted child or step-child), brother-in-law, sister-in-law, son-in-law, daughter-in-law, mother-in-law or father-in-law.
In-patient means a patient who occupies a hospital bed for more than 24 hours for medical treatment and for whom admission was recommended by a doctor when medically necessary.
Injury means bodily damage or harm, sustained by you, directly resulting from an accident that occurs while your coverage under this policy is in force and which requires emergency treatment that is covered by this policy.
Insured, Assured or Insured Person means the person for whom insurance is in force under this policy and who is on file with the plan administrator.
Insurers, Underwriters, Us, Our or We means certain Underwriters at Lloyd's, London who provide this insurance.
International Student means a non-United Kingdom student enrolled in and attending classes in an educational programme at an educational institution, who has had to obtain a student visa and/or temporary visa status for the purpose of pursuing an education within the United Kingdom.
Loss means, in sections pertaining to Accidental Death and Dismemberment benefits:
• with reference to quadriplegia, paraplegia and hemiplegia: the complete and irreversible paralysis of such limbs;
• with reference to hand or foot: complete severance through or above the wrist or ankle joint, but below the elbow or knee joint;
• with reference to arm or leg: complete severance through or above the elbow or knee joint;
• with reference to thumb and index finger: complete severance through or above the first phalange;
• with reference to eye: the irrecoverable loss of the entire sight thereof;
• with reference to speech: complete and irrecoverable loss of the ability to speak;
• with reference to hearing: complete and irrecoverable loss of hearing in both ears;
• with reference to "loss of use": the total and irrecoverable loss of use provided the loss is continuous for 12 consecutive months and such loss of use is determined to be permanent.
Major Diagnostic Testing means diagnoses which require magnetic resonance imaging (MRI), cardiac catheterisation, computed axial tomography (CAT) scans, sonograms, ultrasounds and/or biopsies.
Medical Assistance Provider: Healix Assistance
Medical Treatment means any reasonable medical, therapeutic or diagnostic measure prescribed by a doctor or eligible paramedical practitioner, including prescribed medication, reasonable investigative testing, hospitalisation, surgery or other prescribed or recommended treatment directly referable to the condition, symptom or problem.
Medically Necessary means the services or supplies provided by a hospital, doctor, dentist or other licensed provider that are required to identify or treat your sickness or injury and that are defined as follows:
• consistent with the symptom or diagnosis and treatment of your sickness or injury;
• appropriate with regard to standards of good medical practice;
• not solely for the convenience of you, a doctor or surgeon or other licensed provider; and
• when applied to the care of an in-patient, it further means that your medical symptoms or conditions require that the services cannot be safely provided as a hospital outpatient.
Minor Ailment means any sickness or injury which does not require:
a) the use of medication for a period of greater than 15 days; or
b) more than one follow-up visits to a doctor, hospitalisation or surgical intervention; or
c) referral to a specialist; and
d) which ends at least 30 consecutive days prior to the start date of coverage.
A chronic condition or any complication of a chronic condition is not considered a minor ailment.
Mountain Climbing means the ascent or descent of a mountain requiring the use of specified equipment including crampons, pickaxes, anchors, bolts, carabiners and lead-rope or top rope anchoring equipment.
Parent or Legal Guardian means the natural or adoptive parent, or another adult, who is responsible for the care of, and lives at the same residential address as, an international student under the age of 18.
Participant means a non-United Kingdom individual member of a group such as a club, social association, amateur sports team, day care centre, religious or charitable organisation, volunteer, civic, community service or recreational organisation.
Plan Administrator means MHS International UK Ltd.
Reasonable and Customary means the amount usually charged for treatment, services or supplies to provide an appropriate level of care given the severity of the sickness or injury being treated, in the geographical location where the treatment, services or supplies are being provided.
Remote Country means an area that is not marked, not patrolled and/or not cleared for avalanche dangers, but where public access is permitted.
Sickness: Any illness or disease contracted by an Insured Person which causes the Insured Person to incur medical expenses.
Spouse means a person related to you in one of the following ways:
• legally married to you or in a civil union or civil partnership; or
• living with you in a conjugal relationship and represented as your spouse or partner.
Stable means any medical condition whether or not the diagnosis has been determined, other than a minor ailment, for which there has been:
a) no hospitalisation; and
b) no new diagnosis, treatment or prescribed medication; and
c) no alteration* in treatment or medication; and
d) no new, more frequent or more severe symptoms; and
e) no new test results showing deterioration; and
f) no referral to a specialist (made or recommended) and you are not awaiting surgery or the results of further investigations performed by any medical professional.
*Alteration includes a new medication, stopped medication, increase or decrease medication, but does NOT include changes between brand-name and generic versions of medication with the same active ingredient and dosage or the routine adjustment of maintenance medications such as insulin, coumadin or warfarin.
Teacher means an individual in the education profession who is temporarily visiting the United Kingdom for the purposes of accompanying one or more international students and/or whose visit is sponsored by an educational institution as part of a cultural exchange or similar programme.
Terminal Illness means you have a condition that is cause for the doctor to estimate that you have less than 6 months to live
United Kingdom means England, Scotland, Wales and Northern Ireland. It does not include the Channel Islands or the Isle of Man.
Vehicle means a mechanically propelled vehicle intended or adapted for use on roads which is owned or rented by you from a commercial rental agency for your use during your covered trip.
You or Your means the insured person.
Section 9: Glossary
The words and phrases below have the following meanings. They will appear in bold in this guide.
Acute condition
Annual renewal date
Scheme Benefit, Scheme Benefits
Biological therapies
Cancer
Chronic condition
- requires ongoing or long-term monitoring through consultations, examinations, check-ups and / or tests
- needs ongoing or long-term control or relief of symptoms
- requires rehabilitation or for you to be specially trained to cope with it
- continues indefinitely
- has no known cure, or
- comes back or is likely to come back. <
Complementary practitioner
- Acupuncture practitioners must be registered with the BMAS (British Medical Acupuncture Society), BacC (British Acupuncture Council), AACP (Acupuncture Association of Chartered Physiotherapists) or AAC (The Association of Acupuncture Clinicians)
- Osteopaths must be registered with the GOsC (General Osteopathic Council)
- Chiropractors must be registered with the GCC (General Chiropractic Council)
Day case
Dependant, Dependants
- a employee's unmarried dependant children
Addiction treatment programme
Treatment date
Experimental treatment
- the harmful effects are outweighed by the beneficial effects
- they are likely to lead to the same or better outcomes than available alternatives
- they are based on established medical practice in the United Kingdom <
Private hospital, Private hospitals
NHS hospital, NHS hospitals
Dependant child, Dependant child's, Dependant children, Dependant children's
Emergency repatriation
Primary Care
The Healix Team
Our experienced claims team are available to advise and help you, and can be contacted via the below:
UK telephone support is available Monday-Friday 08.00-19.00 (Excl. bank holidays)
International telephone support is available 24 hours a day, 7 days a week.
Our operating hours are: Monday-Friday 09.00-17.00 (Excl. bank holidays)
Please note, telephone calls to and from our organisation are recorded for the purposes of quality and training.
StudyInsured Scheme
Claims Administration Department
Healix Health Services, Healix House,
Esher Green, Esher, Surrey
KT10 8AB
Section 9: Glossary
The words and phrases below have the following meanings. They will appear in bold in this guide.
Acute condition
Annual renewal date
Scheme Benefit, Scheme Benefits
Biological therapies
Cancer
Chronic condition
- requires ongoing or long-term monitoring through consultations, examinations, check-ups and / or tests
- needs ongoing or long-term control or relief of symptoms
- requires rehabilitation or for you to be specially trained to cope with it
- continues indefinitely
- has no known cure, or
- comes back or is likely to come back. <
Complementary practitioner
- Acupuncture practitioners must be registered with the BMAS (British Medical Acupuncture Society), BacC (British Acupuncture Council), AACP (Acupuncture Association of Chartered Physiotherapists) or AAC (The Association of Acupuncture Clinicians)
- Osteopaths must be registered with the GOsC (General Osteopathic Council)
- Chiropractors must be registered with the GCC (General Chiropractic Council)
Day case
Dependant, Dependants
- a employee's unmarried dependant children
Addiction treatment programme
Treatment date
Experimental treatment
- the harmful effects are outweighed by the beneficial effects
- they are likely to lead to the same or better outcomes than available alternatives
- they are based on established medical practice in the United Kingdom <